Portfolio Open Risk and Position Heat Tracker - India [SMC]WHAT THIS DOES
Position sizing tells you how much to buy on one trade. It says nothing about what happens when you are holding eight of them at once.
This tracks all your open positions together. Pick up to twenty symbols, give each one a quantity, an entry and a stop, and it prices what you are carrying: what you lose if every stop fills, which sectors that loss is concentrated in, and how much room is left before you reach the total loss you are willing to take.
TWO NUMBERS THAT ARE NOT THE SAME
Most risk calculators quietly conflate these. They answer different questions and both are worth knowing.
OPEN LOSS
what you give back from today's price down to your stops. Money currently on the table.
LOSS VS COST
what you lose measured from your entries. On a position whose stop has been trailed above cost this is zero, no matter how much open loss it still carries. A trader running trailed stops can be carrying a large open loss and no loss at all against cost. One number says exposed, the other says protected. Both are true, so the dashboard prints both.
The sample position in WIPRO shows it: stop at 172 against a 170 entry. Real open loss, zero loss against cost.
THE ARITHMETIC
Open loss = Qty x (Last - Stop)
Loss vs cost = Qty x max(0, Entry - Stop)
P&L = Qty x (Last - Entry)
Deployed = sum of Qty x Last
Room left = Max total open loss - Open loss
A position trading below its stop is counted as zero open loss and flagged "past stop", because that loss is already realised. Counting it again would flatter the total.
YOUR LIMIT, NOT MINE
You set the maximum total open loss in rupees. The default of thirty thousand is six percent of the default capital, being six trades at one percent each. That is a common starting point, not a rule from this script. Set it to what you actually run.
The bar fills toward your number. Room left translates whatever remains into a rough count of further trades at your standard risk per trade.
SECTOR CLUSTERING
Open loss is grouped by sector, taken automatically from exchange data. This exists because five positions in one sector is not five independent risks.
Total risk can look comfortable while sitting almost entirely in one group. In the sample portfolio three of five positions are Technology Services and carry half the open loss. The headline number never shows that. The sector block does.
THE POSITION TABLE
Rows sort by open loss, heaviest first, so the position you would feel most is not buried at the bottom. Note that this ordering is not P&L ordering. A stock up five percent with a trailed stop can sit last, because it has the least left on the table.
Entry, stop and last are reference prices and are shown muted. P&L and open loss are the numbers you act on and stay at full strength. A stop above cost is shown in the up colour, which is a fact about the position, not a view on the trade.
GETTING STARTED
The first five rows arrive filled with sample positions so the dashboard shows something useful before you type anything. Replace them with your own. A row counts once it has a symbol, a quantity and a stop. Entry is optional, though without it P&L and loss vs cost cannot be worked out.
Pine cannot add input rows on demand, so all twenty exist from the start and empty ones are ignored.
WHAT THIS DOES NOT DO
It does not know your real broker positions, so what you type is what it believes. It does not tell you whether any position is worth holding, whether your stops are sensible, or whether you are too concentrated. It measures. The judgement stays with you.
LIMITATIONS
Long positions only. Figures exclude brokerage, exchange and statutory charges, taxes, slippage, partial fills, and gap risk. Gap risk matters most here: if several positions gap below their stops at once, the total loss will exceed every figure shown, and no dashboard can prevent that. Open loss assumes each stop fills at its exact price. Treat it as a floor. Prices are daily closes for each symbol and update while the session is open. Positions whose symbol cannot be priced are excluded from every total and
flagged.
Educational and decision-support only. Not investment advice, and not a recommendation to buy or sell any security. Индикатор

[Kpt-Ahab] Savings Plan IND Savings Plan Indicator
This indicator simulates and documents a complete savings plan directly on the TradingView chart. Deposits, dividends, purchases, sales, and costs are processed through a shared savings-plan account, making the cash balance and cash flow transparent and traceable.
Features:
- Initial capital with first purchase
- Regular deposits with optional periodic increases
- Fractional or whole units
- Automatic use of available cash when the regular DCA budget is insufficient to purchase the minimum tradable quantity
- Chart warning when a DCA purchase cannot be executed
- Four manual or adaptive DIP-buy levels
- Automatic profiles: Defensive, Balanced, and Aggressive
- Manual or automatic profit taking with trailing and cash rebalancing
- Minimum price increase required between two TP sales
- Transactions at the confirmed bar close or at the bar open
- Dividend processing
- Transaction, broker, custody, and dividend costs
- TradingView alerts for DCA, DIP, and TP events
- Detailed purchase and sale labels
- Marking of the highest profit point and the largest portfolio drawdown
- Full statistics table or compact mobile view
- Tables, labels, and alert messages in English, German, or French
The statistics include, among other values, deposits, cash balance, units held, cost basis, market value, portfolio value, realized and unrealized results, total costs, drawdowns, cumulative return, and the annualized return (XIRR).
Mobile Table
A reduced mobile view can be enabled for smaller screens. It displays the most important portfolio, return, drawdown, cost, and transaction information using shorter labels and smaller text.
Transaction and Alert Notes
With "Confirmed close", signals are triggered only after the bar has been confirmed at its closing price. On daily charts, the exchange may already be closed by the time the signal becomes available.
With "Bar open", the evaluation is performed at the opening price of the new bar. The Auto model uses only confirmed data from the previous bar. The opening price of the new bar is not necessarily identical to the previous closing price, for example when a price gap occurs.
The indicator does not place real orders. Automatic settings and historical results do not guarantee future performance and do not constitute investment advice.
Индикатор

CapitalCompassCoreCapital Compass Core
Capital Compass Core is the shared Pine Script framework for the Capital Compass ecosystem. It centralizes reusable calculations, state definitions, visual standards, market-context logic, risk logic, portfolio helpers, strategy utilities, panel functions, formatting tools, and alert infrastructure used across Capital Compass scripts.
The library is designed to keep Market Navigator, Tactical Navigator, Strategy Lab, Portfolio Compass, and future Capital Compass tools operating from the same definitions instead of maintaining duplicate implementations across multiple scripts.
Purpose
Capital Compass Core is infrastructure rather than a standalone trading indicator.
The library calculates and standardizes reusable logic. Consuming indicators and strategies remain responsible for user inputs, plots, fills, chart markers, alert conditions, strategy orders, and script-specific interpretation.
Core calculates and standardizes. The consuming script orchestrates and renders.
Core systems
Reusable functionality includes:
• EMA, SMA, RMA, WMA, VWMA, HMA, DEMA, TEMA, and VWAP
• Moving-average structure, compression, expansion, zones, crosses, and standardized MA hierarchy
• 20-SMA / 21-EMA Fast Trend Zone
• Ichimoku calculations
• Bollinger Bands
• ATR, relative volume, drawdown, price-shock, and volatility calculations
• SuperTrend and multi-SuperTrend agreement
• RSI/MFI/MACD momentum components and consolidated momentum states
• Market regime, risk, opportunity, and market-permission scoring
• Tactical market phases and transition states
• Market Navigator state aggregation
• Price structure, pivots, and regular divergence
• Asset-profile presets
• Portfolio allocation and deployment calculations
• Account-context helpers
• Position sizing, ATR stops, targets, trailing logic, reward/risk, R multiples, expectancy, and strategy-quality helpers
• Confirmed higher-timeframe data helpers
• Relative-strength calculations
• Alert-event routing and transition helpers
• JSON and text formatting
• Theme-aware panels, table cells, text, borders, fills, and semantic state backgrounds
State and color standard
Capital Compass uses a consistent semantic visual language:
• Green = bullish / favorable
• Red = bearish / unfavorable
• Orange = caution / transition / sideways / neutral / mixed
• Gray = inactive / unavailable / insufficient data
• Blue = informational / fast-trend reference
• Magenta = major structural reference
Moving-average identity colors are separate from directional state colors. This allows a moving average to retain a recognizable identity while optional Trend mode communicates bullish, bearish, or transitional conditions.
The standardized moving-average hierarchy includes:
8, 13, 20, 21, 34, 50, 55, 89, 100, and 200 periods.
Primary structural references:
• 20 / 21 = fast trend
• 50 / 55 = intermediate trend / caution zone
• 200 = major long-term structural reference
Capital Compass Core also provides theme-aware helpers derived from the active TradingView chart colors so consuming scripts can remain readable across light and dark chart themes.
Capital Compass ecosystem
Market Navigator
Long-term market condition, regime, risk, opportunity, portfolio context, and review.
Tactical Navigator
Tactical trend, momentum, transition, Fast Trend Zone, volatility, and market-phase analysis.
Strategy Lab
Research, hypothesis testing, backtesting support, position sizing, risk planning, and strategy evaluation.
Portfolio Compass
Portfolio allocation, deployment, account context, and long-term capital-management support.
Shared calculations should be imported from Capital Compass Core rather than independently duplicated inside each script.
Library usage
Import the library with:
import DrGetDown/CapitalCompassCore/1 as CC
Examples of shared functionality include:
CC.ma(...)
CC.maColor(...)
CC.fastTrendZone(...)
CC.marketNavigatorState(...)
CC.tacticalPhase(...)
CC.momentumScore(...)
CC.stateColor(...)
CC.panelPos(...)
CC.strategyPlan(...)
Published library versions are intentionally explicit. Consuming scripts should migrate only after a newer Core release has been compiled, tested, and validated.
Design principles
• Maintain one definition for shared calculations and state meanings.
• Separate market-state colors from moving-average identity colors.
• Keep reusable calculations in Core whenever technically practical.
• Keep script-specific interpretation and rendering in the consuming script.
• Avoid unnecessary duplicate or correlated calculations.
• Use confirmed higher-timeframe data where explicitly specified.
• Keep risk and position-sizing mathematics separate from actual strategy order placement.
• Preserve consistent panel placement, formatting, abbreviations, state meanings, and visual behavior across the ecosystem.
• Test significant shared changes before promoting them across dependent Capital Compass scripts.
Limitations
Capital Compass Core does not predict future prices and does not guarantee profitable trades or prevent losses.
Market regimes, momentum states, tactical phases, opportunity scores, risk scores, divergences, moving-average structures, and strategy statistics are analytical classifications based on supplied market data and configured assumptions. They should not be interpreted as guarantees of future performance.
Backtest statistics describe historical results and do not guarantee similar future results.
Portfolio, allocation, deployment, and position-sizing helpers provide mathematical and analytical context only. Actual decisions remain dependent on objectives, portfolio circumstances, risk tolerance, time horizon, liquidity needs, taxes, diversification, and independent research.
Version
Internal Core version: 1.0.0
TradingView library release: /1
Capital Compass
OBSERVE • DISCERN • PREPARE • ACT WISELY
Tuned to the signal. Anchored to the mission. Библиотека

Global Macro RegimeThe Global Macro Regime is a top-down macro nowcasting and portfolio allocation tool that provides a consolidated view of the market-implied macro regime. It independently evaluates 30 key global markets across equities, fixed income, commodities, and currencies to determine the prevailing macro regime, which informs the model’s portfolio preferences and regime-specific exposures. It also features built-in alerts and an integrated backtester that enable investors to monitor regime changes and evaluate asset performance across different macro environments.
At its core, the model aggregates 30 independent cross-asset market signals to identify shifts in the market’s growth and inflation outlook. Rather than relying on backward-looking economic data, the model derives these signals in real time from evolving trends across global markets. By focusing on growth and inflation, the model captures two of the primary macroeconomic forces driving asset prices. The four possible combinations of growth and inflation define four distinct macro regimes, each of which tends to favor different portfolio preferences and exposures:
Goldilocks (Growth ↑, Inflation ↓): Improving growth with low/declining inflation.
Reflation (Growth ↑, Inflation ↑): Improving growth with high/rising inflation.
Inflation (Growth ↓, Inflation ↑): Deteriorating growth with high/rising inflation.
Deflation (Growth ↓, Inflation ↓): Deteriorating growth with low/declining inflation.
Goldilocks and Reflation represent Risk-On regimes, while Inflation and Deflation represent Risk-Off regimes. Each of the 30 selected markets is evaluated independently as either a growth or inflation signal. Markets signaling improving growth contribute to both Goldilocks and Reflation, while markets signaling deteriorating growth contribute to both Inflation and Deflation. Markets signaling high/rising inflation contribute to both Reflation and Inflation, while markets signaling low/declining inflation contribute to both Goldilocks and Deflation. The selected markets are grouped into equities (10), fixed income (10), commodities (6), and currencies (4):
Equities = S&P 500 Index (SPX), Russell 2000 Index (RUT), STOXX Europe 600 Index (SXXP), Nikkei 225 Index (NI225), Hang Seng Index (HSI), MSCI Emerging Markets Index Futures (MME), High Beta / Low Volatility Ratio (SPHB/SPLV), Cyclicals / Defensives Ratio (XLY/XLP), S&P 500 Volatility Index (VIX), and 3M Implied Correlation Index (COR3M).
Fixed Income = US 2Y Treasury Yield, US 10Y Treasury Yield, German 10Y Bund Yield, UK 10Y Gilt Yield, Japan 10Y JGB Yield, US 10Y Breakeven Inflation Rate, US CCC Distressed Index Option-Adjusted Spread, US High Yield Index Option-Adjusted Spread, US Investment Grade Corporate Index Option-Adjusted Spread, and US Bond Volatility Index (MOVE).
Commodities = Brent Crude Oil Futures (BRN), Agricultural Commodities (DBA), Industrial Metals (DBB), Copper Futures (HG), Silver / Gold Ratio (SI/GC), and CME Bitcoin Futures.
Currencies = US Dollar Index (DXY), Australian Dollar / US Dollar (AUDUSD), British Pound / US Dollar (GBPUSD), and Euro / US Dollar (EURUSD).
Each market signal is derived independently using either a volatility-adjusted moving-average crossover, a volatility-based adaptive trailing stop, or a combination of both. The signals are then aggregated and normalized into percentage scores representing each regime’s share of total signals, with optional smoothing over the specified signal length to reduce noise. The regime receiving the greatest confirmation across global markets is identified as the dominant macro regime and translated into portfolio preferences displayed in the regime preference table:
Goldilocks Preferences = Risk-On > Risk-Off, High Beta > Low Beta, Cyclicals > Defensives, International < US Equities, SMID Caps < Large Caps, Short Rates > Long Rates, Spreads > Treasuries, High Yield > Low Yield, Beta FX > US Dollar, Metals > Energy, and Bitcoin > Gold.
Reflation Preferences = Risk-On > Risk-Off, High Beta > Low Beta, Cyclicals > Defensives, International > US Equities, SMID Caps > Large Caps, Short Rates > Long Rates, Spreads > Treasuries, High Yield > Low Yield, Beta FX > US Dollar, Metals > Energy, and Bitcoin > Gold.
Inflation Preferences = Risk-On < Risk-Off, High Beta < Low Beta, Cyclicals < Defensives, International < US Equities, SMID Caps < Large Caps, Short Rates > Long Rates, Spreads < Treasuries, High Yield < Low Yield, Beta FX < US Dollar, Metals < Energy, and Bitcoin < Gold.
Deflation Preferences = Risk-On < Risk-Off, High Beta < Low Beta, Cyclicals < Defensives, International < US Equities, SMID Caps < Large Caps, Short Rates < Long Rates, Spreads < Treasuries, High Yield < Low Yield, Beta FX < US Dollar, Metals > Energy, and Bitcoin < Gold.
The model further translates these portfolio preferences into specific exposures across equities, fixed income, commodities, and currencies. The selected exposures have been systematically backtested across the four macro regimes, dating back as far as January 1996, to identify those exhibiting the strongest risk-adjusted performance and most consistent directionally aligned trending behavior within each asset class. The resulting exposure lists provide a more granular view of the model’s broader portfolio preferences based on historically observed relationships:
Goldilocks Exposures = Equity sectors include Communication Services (XLC), Technology (XLK), Financials (XLF), Industrials (XLI), Consumer Discretionary (XLY), Materials (XLB), and Real Estate (VNQ). Equity factors include S&P 500 (SPY), Nasdaq 100 (QQQ), High Beta (SPHB), Momentum (MTUM), Quality (QUAL), Growth (IWF), and Value (IWD). Fixed income includes High Yield Bonds (HYG), Investment Grade Bonds (LQD), and Convertible Bonds (CWB). Commodities include Bitcoin (BTC), Industrial Metals (DBB), Metal Producers (PICK), Gold (GLD), Gold Miners (GDX), Silver (SLV), Silver Miners (SIL), Copper (CPER), Copper Miners (COPX), Uranium (SRUUF), and Uranium Miners (URNM). Currencies include Australian Dollar (FXA), British Pound (FXB), and Euro (FXE).
Reflation Exposures = Equity sectors include Energy (XLE), Communication Services (XLC), Technology (XLK), Financials (XLF), Industrials (XLI), Consumer Discretionary (XLY), Materials (XLB), and Real Estate (VNQ). Equity factors include Global Equities (ACWI), International Equities (ACWX), S&P 500 (SPY), Nasdaq 100 (QQQ), Emerging Markets (EEM), High Beta (SPHB), Mid Caps (IWR), Small Caps (IWM), Momentum (MTUM), Quality (QUAL), Growth (IWF), Value (IWD), Equal Weight (RSP), Global Infrastructure (IGF), and International Real Estate (IFGL). Fixed income includes High Yield Bonds (HYG), Convertible Bonds (CWB), Private Credit (BIZD), and Emerging Market Bonds (EMB). Commodities include Bitcoin (BTC), Commodities (DBC), Industrial Metals (DBB), Metal Producers (PICK), Crude Oil (USO), Agriculture (DBA), Agriculture Producers (VEGI), Gold (GLD), Gold Miners (GDX), Silver (SLV), Silver Miners (SIL), Copper (CPER), Copper Miners (COPX), Uranium (SRUUF), and Uranium Miners (URNM). Currencies include Australian Dollar (FXA), Canadian Dollar (FXC), British Pound (FXB), and Euro (FXE).
Inflation Exposures = Equity sectors include Energy (XLE), Consumer Staples (XLP), Utilities (XLU), and Health Care (XLV). Equity factors include Low Volatility (SPLV). Fixed income includes 1-3 Month Treasury Bills (BIL). Commodities include Commodities (DBC), Crude Oil (USO), Agriculture (DBA), and Gold (GLD). Currencies include US Dollar (UUP).
Deflation Exposures = Equity sectors include Consumer Staples (XLP), Utilities (XLU), and Health Care (XLV). Equity factors include Low Volatility (SPLV) and High Dividend (SPHD). Fixed income includes 1-3 Year Treasuries (SHY), 7-10 Year Treasuries (IEF), 20+ Year Treasuries (TLT), US Aggregate Bonds (AGG), Mortgage-Backed Securities (MBB), and International Aggregate Bonds (BNDX). Commodities include Gold (GLD). Currencies include US Dollar (UUP) and Japanese Yen (FXY).
The model includes a built-in alert system that notifies investors in real time when the dominant macro regime changes and provides the corresponding exposures for the new regime. It also features an integrated backtesting engine that can be enabled in the menu to evaluate asset performance across the macro regimes. Users can assign an asset to each regime, with the backtest automatically rotating into the corresponding asset whenever that regime becomes dominant. If one or more assets are assigned, any unassigned regimes are treated as cash. If no assets are assigned, the chart ticker is assigned to Goldilocks and Reflation, while Inflation and Deflation are treated as cash. The backtest reports the following performance metrics:
CAGR = Compounded Annual Growth Rate.
Excess = CAGR in excess of buy-and-hold.
Sharpe = CAGR per unit of standard deviation.
Sortino = CAGR per unit of downside deviation.
Calmar = CAGR relative to maximum drawdown.
Max DD = Largest peak-to-trough decline in value.
Alpha (α) = Excess annualized risk-adjusted returns.
Win Rate = Ratio of profitable trades to total trades.
Profit Factor = Total gross profit per unit of losses.
Expectancy = Average expected return per trade.
Turnover = Average annualized change in exposure.
The indicator is designed with flexibility in mind, allowing users to select the backtest period, signal methodology, preferred trend type, volatility type, and the individual markets included in the regime calculation. Supported moving-average types include the Exponential Moving Average (EMA), Simple Moving Average (SMA), Wilder’s Moving Average (RMA), and Weighted Moving Average (WMA). Supported volatility types include the Average True Range (ATR), Standard Deviation (SD), and Mean Absolute Deviation (MAD). The table follows an intuitive color-coded logic that allows for quick performance comparison against buy-and-hold (B&H):
CAGR = Green indicates above 0%, while red indicates below 0%.
Excess = Green indicates above 0%, while red indicates below 0%.
Sharpe = Green indicates better than B&H, while red indicates worse.
Sortino = Green indicates better than B&H, while red indicates worse.
Calmar = Green indicates better than B&H, while red indicates worse.
Max DD = Green indicates better than B&H, while red indicates worse.
Alpha (α) = Green indicates above 0%, while red indicates below 0%.
Win Rate = Green indicates above 50%, while red indicates below 50%.
Profit Factor = Green indicates above 2, while red indicates below 1.
Expectancy = Green indicates above 0%, while red indicates below 0%.
In summary, the Global Macro Regime is a comprehensive market-based macro framework designed to identify the prevailing macro regime. By combining 30 independent cross-asset market signals, the model translates the dominant macro regime into portfolio preferences and regime-specific exposures based on historical relationships that may not persist under future market conditions as market dynamics and asset-specific characteristics evolve over time. Historical coverage also varies across the 30 selected markets, with regime signals prior to 2006 based on progressively fewer markets and therefore requiring more cautious interpretation. Индикатор

Strong Tech Stocks Screener | ProjectSyndicateStrong Tech Stocks Screener turns dozens of charts into a single institutional-style dashboard, ranking a curated universe of 40 leading tech, AI, and semiconductor names by performance across six timeframes and scoring each one on professional-grade risk metrics — Beta, Sharpe, Sortino, Omega, Z-Score, and Kelly — so you can find the leaders and weigh their risk-adjusted quality at a glance, all on one clean, sortable panel. Every figure is computed live on the daily timeframe from real price history, not hard-coded, so the board reflects the market as it actually is right now.
📊 Curated 40-Name Tech Universe — the screener watches a hand-picked list of 40 high-momentum tech, AI, and semiconductor stocks in one place. Instead of flipping through forty charts, you see every name's performance and risk profile side by side and immediately spot who is leading and who is rolling over.
🗓️ Six-Timeframe Performance — each stock is tracked across Week, Month, Quarter, 6-Month, 12-Month, and Year-to-Date returns, so you can separate a one-week pop from a genuine long-run trend and see momentum building or fading across horizons in a single row.
🧮 Institutional Risk Metrics, Done Properly — beyond raw returns, every name is scored on Sharpe (excess return per unit of total volatility), Sortino (return per unit of downside risk only), Omega (probability-weighted gains versus losses above the risk-free threshold), Z-Score (how stretched the recent move is in standard deviations), and the Kelly fraction (a theoretical optimal-sizing read from return and variance). The stats are annualized from daily returns over a rolling window with a configurable risk-free rate, so the risk picture is consistent and comparable across the whole list.
🎯 Basket-Relative Beta — Beta is measured against an equal-weight basket of the 40 names in the screener, so it tells you how a stock moves relative to this specific tech/AI cohort rather than a broad index. Beta above 1 swings harder than the group; below 1 is steadier. You control the lookback length used for the beta and correlation calculation.
🌡️ Annualized Weekly Volatility — a dedicated Wk Vol column annualizes the standard deviation of recent weekly returns, giving you a fast read on how violent each name's price action is before you size into it.
🔀 Dynamic Sorting — sort the entire board by any of the six performance columns with a single setting. Rank by YTD to find the year's leaders, by Week to catch what is moving now, or by any horizon in between — the table re-ranks instantly.
🎨 Bloomberg-Amber Theme with Color-Coded Strength — a clean amber-on-black dashboard with a multi-level gradient that runs from bright amber on the strongest gains through to deep red on the steepest losses, so strength and weakness jump out the moment you look at the panel.
🧩 Fully Customizable Dashboard — place the table anywhere on the chart (Top / Middle / Bottom paired with Left / Center / Right), choose your text size (Tiny / Small / Normal / Large), set the sort column, the beta length, and the risk-free rate and periods — all from the settings menu, no code editing required.
🔒 Daily-Timeframe Lock — the screener is built for daily data and will prompt you to switch if you load it on a lower timeframe, so the returns, volatility, and ratios are always calculated on the basis they are designed for.
⚡ Lightweight and Efficient — the whole 40-name board is built from a tight, well-organized script that runs smoothly on TradingView, with a clean merged title heading and an alternating-row layout for easy reading.
🎯 Why this is different — most watchlists show you price and maybe a percentage move. This screener puts performance and a full institutional risk stack — Sharpe, Sortino, Omega, Z-Score, Kelly, Beta, and annualized volatility — for forty leading tech names on one sortable, color-coded panel, so you are ranking opportunities by risk-adjusted quality, not just chasing the biggest green number.
🚀 Where to use it — apply it to any daily chart to monitor the tech/AI/semiconductor leadership group as a whole. Use it for top-down scanning, rotation ideas, and risk screening before you drill into an individual name's chart for entry timing.
⚠️ Important — this is a research and decision-support dashboard, not a buy/sell system, and it makes no performance guarantees. All figures are historical and descriptive, computed from past price data, and say nothing certain about the future. Risk metrics like Sharpe, Sortino, Omega, Z-Score, and Kelly are simplified, assumption-based estimates and should inform your judgment, not replace it. Always pair the screener with your own analysis and risk management. Индикатор

Multi-Strategy Portfolio Optimizer [LuxAlgo]The Multi-Strategy Portfolio Optimizer indicator is a comprehensive quantitative tool that evaluates 9 distinct trading setups across trend-following, momentum, and mean-reversion categories to construct an optimized, equally-weighted portfolio.
🔶 USAGE
This script aims to help users identify which trading methodologies are currently performing best on a specific ticker and timeframe, while simultaneously monitoring how well those strategies diversify each other to create a smoother equity curve.
🔹 Strategy Selection & Evaluation
The optimizer evaluates three unique parameter variations for each of the following 9 strategy types:
Supertrend & EMA Crossovers: Captures sustained directional trends.
MACD & CCI: Focuses on momentum shifts and overextended breakouts.
Donchian Channels: Classic breakout logic based on price extremes.
RSI Trend: Uses RSI levels to confirm momentum direction.
RSI Rev, Bollinger Bands & Stochastic: Targets mean-reversion and overbought/oversold exhaustion.
The tool automatically selects the "Best Setting" for each category by comparing the cumulative performance of all three variations across the available chart history. Only the top-performing variation from each category is included in the final portfolio calculation.
🔹 Equity Dashboards
The indicator features two primary visual interfaces to monitor performance and risk:
Floating Curves Box: Displays a real-time equity curve of the total portfolio (thick white line) against the individual active strategies (faded colored lines). This allows users to see the recent performance stability over a user-defined lookback.
Correlation Heatmap: Analyzes the statistical relationship between active strategies. This table uses color-coding to show how similar or different strategy returns are, providing a "Diversification Grade" (e.g., Excellent, Good, Poor) to help users avoid over-exposure to a single market regime.
🔹 Trade Visualization
Users can enable "Show Past & Open Trades" to audit the simulated performance directly on the price action. The script plots entry lines and shaded ATR-based Stop Loss (red) and Take Profit (green) zones for both currently active and historical trades.
🔶 DETAILS
🔹 Best Setting Logic
For every strategy category, the script runs three parallel simulations with different sensitivity settings. The "Best Setting" displayed in the dashboard is the variation that has achieved the highest cumulative percentage return since the beginning of the chart.
🔹 Portfolio Calculation (Equal Weight)
The Portfolio Equity Curve is calculated by averaging the cumulative returns of all active "best" setups on a bar-by-bar basis. This simulates an equally weighted allocation where the capital is distributed evenly across all chosen trading methodologies, aiming to reduce the drawdown typically associated with a single-strategy approach.
🔹 Diversification & Correlation
The Heatmap calculates a Pearson correlation coefficient over a rolling 100-bar window for every pair of active strategies.
Correlation > 0.7 (Red): Strategies are moving in lockstep, offering little diversification.
Correlation near 0 (Yellow): Strategies are independent, providing healthy diversification.
Correlation < -0.2 (Green): Strategies are inversely correlated, which can significantly hedge portfolio volatility.
🔹 Auto-Scaling Polylines
The floating curves dashboard uses a dynamic normalization algorithm. It captures the highest and lowest equity values within the user-defined lookback (Curves Length) and scales them to fit within the box height. This ensures the curves remain visible and proportional regardless of whether the returns are 1% or 100%.
🔶 SETTINGS
🔹 Strategies
Enable : Toggles whether a specific strategy category is evaluated and included in the portfolio math.
🔹 Risk Management
Enable Stop Loss & Take Profit: Toggles the ATR-based exit engine.
ATR Length: The period used for calculating volatility-based exits.
Stop Loss / Take Profit Mult: The multipliers that define the distance of exit targets from the entry price.
Show Past & Open Trades: Visualizes the execution zones on the chart.
🔹 Dashboard
Main Dashboard / Correlation Heatmap: Toggles the visibility of the tables.
Position: Moves the UI elements to different corners of the chart.
Curves Length: Determines the lookback for the floating equity chart.
Curves Vertical Position: Allows you to pin the curves box to the Top, Middle, or Bottom of the price range.
Curves Box Height (%): Adjusts the vertical scale of the equity chart relative to the price action.
Size: Controls the scale of the text and tables (Tiny to Huge). Индикатор

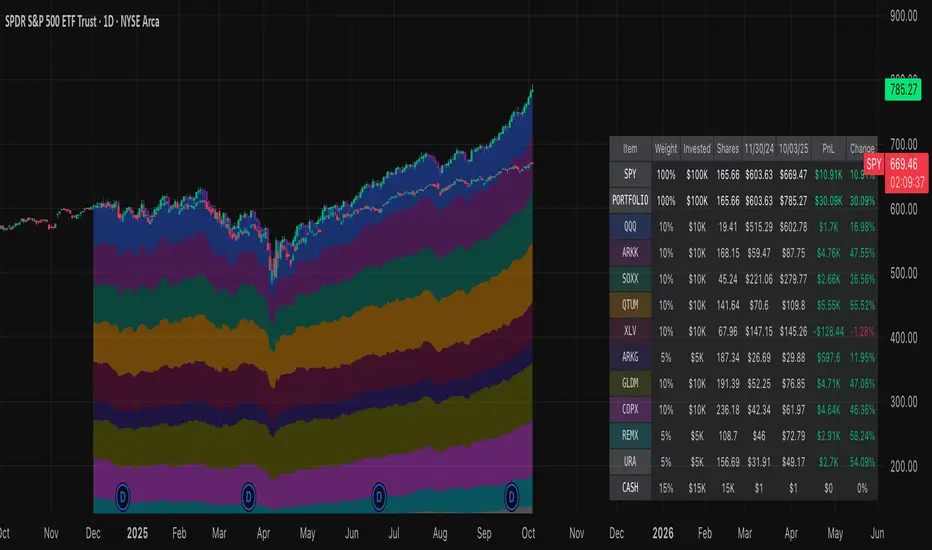
Portfolio Treemap [invincible3]Portfolio Treemap
Portfolio Treemap is a visual portfolio monitoring dashboard designed to help traders and investors track multiple holdings directly on the TradingView chart.
The indicator allows users to enter up to 20 instruments, including stocks, ETFs, crypto pairs, forex symbols, or other TradingView-supported assets. For each instrument, the user can define the buy price and number of shares or units held. The script then calculates the live market value, cost basis, unrealized profit/loss, and percentage return using real-time chart data.
The dashboard uses a treemap-style layout where larger boxes represent larger portfolio weight based on the selected ranking mode. Box colors show unrealized performance: green for profitable positions and red for losing positions. The stronger the profit or loss percentage, the stronger the color intensity. Empty cells are blended with the chart background for a cleaner and more professional visual appearance.
Key Features:
• Track up to 20 portfolio instruments
• User-defined portfolio name
• Input symbol, buy price, and shares/units for each holding
• Real-time portfolio value, cost, and unrealized P/L
• Treemap-style visual dashboard
• Profit and loss color gradient
• Green boxes for winning positions
• Red boxes for losing positions
• Dynamic text color for light and dark themes
• Empty cells blend with chart background
• Supports stocks, ETFs, crypto, forex, commodities, and indices
• Adjustable dashboard position and size
• Optional portfolio header
• Multiple box-ranking modes: shares, position value, absolute P/L, and absolute P/L %
How to Use:
1. Add the indicator to your chart.
2. Open the indicator settings.
3. Enter your portfolio name.
4. Select each portfolio symbol.
5. Add your average buy price.
6. Add your number of shares or units.
7. Choose how boxes should be ranked: by shares, position value, absolute P/L, or absolute P/L percentage.
8. Use the dashboard to monitor portfolio performance visually.
Color Logic:
• Green = position is in profit
• Red = position is in loss
• Stronger color = larger percentage move
• Neutral color = near breakeven
• Empty spaces blend with the chart background
Important Notes:
For best results, use instruments quoted in the same currency. Mixing assets quoted in different currencies may make the total portfolio value and P/L less accurate unless the user manually adjusts values.
This indicator is intended for portfolio visualization and monitoring only. It does not provide buy or sell signals and should not be treated as financial advice. Always confirm portfolio values with your broker or exchange.
Индикатор

Markowitz Frontier Compass [JOAT]Markowitz Frontier Compass
Introduction
Markowitz Frontier Compass compares the chart symbol against a peer basket using inverse-volatility weights, correlation drag, diversification benefit, factor scores, and active risk budget.
This open-source indicator is designed as a context tool, not a standalone trading system. It focuses on explaining the current market state with restrained visuals and confirmed-bar logic where signals are used.
Core Concepts
1. Inverse-Volatility Basket
Each peer receives an inverse-volatility weight to form a portfolio-context benchmark.
2. Correlation Drag
Average pairwise correlation reduces diversification value when assets move together.
3. Factor Composite
Quality, momentum, low-volatility, and carry-style behavior are combined.
4. Risk Budget
Institutional grade, entropy, concentration, and factor state become active or defensive budget context.
frontierScore = efficiency + diversification - correlationDrag - concentration
Features
Peer basket context
Inverse-volatility weighting
Correlation drag and diversification benefit
Factor composite and allocation entropy
Risk-on, defense, and factor-prime states
Input Parameters
Peer symbols
Return window and smoothing
Risk-free annual percent
Correlation stress and concentration gates
Display toggles and HUD position
How to Use This Script
Use MFC as cross-asset context. Risk-on or factor-prime states suggest constructive basket behavior; defense states warn of stress.
Limitations
The script uses historical OHLCV data and cannot know future prices.
Signals and states can be late during fast reversals because confirmed-bar logic is used to reduce repainting.
Model outputs should be interpreted with market context, risk controls, and independent analysis.
No visual state should be treated as a certain trade outcome.
Originality Statement
MFC is original in combining portfolio theory, factor scoring, entropy, and risk-budget logic in one open-source study.
Disclaimer
This indicator is provided for educational and informational purposes only. It is not financial advice, investment advice, or a recommendation to buy or sell any financial instrument. All calculations are derived from historical market data and may produce inaccurate readings in some market conditions. No indicator can predict future market behavior. Use proper risk management and independent judgment.
-Made with passion by jackofalltrades
Индикатор

Индикатор

Xer0's Dual Engine Ladder AllocatorOverview
This indicator is designed for long-term investors using a "Dual Engine" portfolio strategy on M1 Finance — mixing a broad-market index fund with a leveraged counterpart in the same Pie. Instead of guessing when to buy the dip, this script provides a systematic, step-by-step roadmap for increasing your leveraged allocation as the market falls, and resetting it as the market recovers.
How It Works
The strategy is built on "Sticky All-Time High" logic. It tracks the highest close price and calculates the current drawdown from that peak, then responds with one of three scenarios:
Ladder Down (Risk On): For every defined drop step (e.g. every -5%), the indicator signals a RISK UP event — automatically calculating your new target allocation to the leveraged slice of your Pie. This forces systematic, disciplined buying at lower prices.
Recovery Reset (Risk Off): Once the market recovers by a set percentage from the bottom, the script signals a RESET — returning your allocation to the base level and locking in the gains from the dip-buying phase.
Bull Step: When the market pushes into new high territory, the script tracks each new leg up and keeps your reference point current.
Key Features
Sticky ATH Tracking: Automatically calculates true drawdown from the cycle peak
Customizable Ladder Steps: Define your own drop trigger percentage and leverage increase per step
Max Cap: Hard ceiling on leverage exposure to protect against catastrophic drawdowns
Bar Confirmation: All signals fire on daily close to avoid intraday false triggers
Visual Dashboard: Bottom-right table showing current mode, target leverage, drawdown, and recovery price target
Alert Conditions: Built-in RISK UP and RESET alerts compatible with TradingView's "Once Per Bar Close" setting
Backtested Performance (Simulated — Read Carefully)
The following results are from a Python backtest covering approximately 30 years (1996–2026), using $923/week in contributions every Friday. The strategy used two M1 Pies: Pie 1 (S&P 500 index fund / 3× S&P 500 ETF, base leverage 35%) and Pie 2 (Nasdaq-100 index fund / 3× Nasdaq-100 ETF, base leverage 25%). Tax assumptions reflect California state + federal rates for a $47K–$100K income bracket. Data prior to 2010 is synthetic, modeled from underlying index returns.
Results are hypothetical and do not represent actual trading. Past performance does not guarantee future results.
Ladder Strategy | VOO Benchmark
Total Contributed $1,395,576 | $1,395,576
Final Value (after-tax) $25,286,879 | $9,025,443
Total Return 1,711.9% | 546.7%
CAGR (on contributions) 10.1% | 6.4%
Max Drawdown -91.8% | -50.5%
Taxes Paid (CA) $5,358,907 | N/A (buy & hold)
Cash After Full Liquidation $23,500,189 | $7,171,385
The ladder strategy produced approximately 227.7% more after-tax cash than buy-and-hold VOO after full liquidation. However, the strategy experienced a maximum drawdown of -91.8% — meaning at its worst point, the portfolio lost nearly all of its value on paper. This level of volatility is not suitable for most investors and requires strong conviction and a long time horizon to hold through.
How to Use
Add this indicator to a Daily (1D) chart of your chosen index. Configure the inputs to match your risk tolerance — Base Leverage %, Drop Step %, and Max Cap %. Enter your M1 Pie name in the input field so alerts reference it by name. Set alerts using "Once Per Bar Close" and adjust your Pie allocation whenever a signal fires.
Disclaimer
This script is for informational and educational purposes only. It does not constitute financial advice. Backtested results are simulated and hypothetical — they do not account for all real-world frictions and should not be interpreted as a guarantee of future performance. Trading leveraged instruments involves significant risk, including the potential loss of your entire investment, and is not suitable for all investors. Индикатор

Master Portfolio Lab PRO [The Quant Science]The Master Portfolio Lab PRO is an advanced quantitative analysis terminal designed to transform TradingView into a powerful multi-asset portfolio management engine. Developed with institutional-grade calculation logic, this tool allows you to simulate, monitor, and analyze the combined performance of 12 customizable assets within a single, dynamic environment.
In a world where trading is often hyper-focused on a single ticker, the Master Lab enables you to level up: stop looking at the tree and start managing the forest.
🧪 USAGE
The script is designed for traders and investors looking to validate asset allocation strategies or monitor their real-market exposure against a specific benchmark.
🧬 How to configure it:
Asset Allocation: Enter your desired tickers (Crypto, Stocks, Forex, or Commodities) and assign a percentage weight to each slot. Ensure the total weight equals 100%.
Capital Configuration: Choose from predefined capital profiles (from $1k to $1M) or set a custom capital amount for precise simulations.
Costs & Fees: Set a "Portfolio Fee" to reflect transaction costs and generate a realistic, non-theoretical equity curve.
Benchmark Comparison: Select a reference index (e.g., S&P 500 or Bitcoin) to measure the Alpha generated by your active management.
🧪 DETAILS
🧬 Multi-Mode Analysis Engine
The script offers four independent visualization modes, instantly switchable via the settings menu:
Cumulative (%): Comparative analysis between the portfolio's percentage return and the benchmark.
Equity ($): Monetary monitoring of net liquidity and cash growth.
SMA Ribbon: Identification of the portfolio's trend regime using moving averages applied directly to the equity curve.
Volatility: Real-time monitoring of portfolio "thermal stress" via smoothed Standard Deviation (WMA).
🧬 Alpha-Glow Logic
The system utilizes a high-fidelity visual architecture based on dynamic gradients. When the portfolio outperforms the benchmark (Positive Alpha), the fill area illuminates, providing immediate psychological feedback on the quality of your management.
🧬 Real-Time Dashboard
An integrated table in the bottom-right corner processes live data to provide:
Net Value: Current portfolio value, including PnL and costs.
Return %: Total return from the selected starting anchor point.
Alpha vs Index: The "holy grail" of trading—exactly how much value you are adding compared to a passive investment.
🧪 SETTINGS
🧬 Capital Configuration
1) Fixed Capital: Toggle quick selectors for standard account sizes.
2) Custom Capital: Manual input for simulating specific real-world accounts.
🧬 Date Period Analysis
Allows you to set a precise start date (Day/Month/Year) to analyze portfolio performance during specific macroeconomic events or historical cycles.
The Master Portfolio Lab PRO was born from the need to overcome TradingView's native limitations in multi-symbol management. By utilizing normalization techniques and iterative Rate of Change (ROC) calculations, we have created a framework capable of simulating an entire investment fund with surgical precision. Индикатор

Risk Management & Position size calculator (FinPip)# Risk Management & Position size calculator (FinPip)
**Size your trades by risk.** Set your capital, risk %, entry and stop-loss — the indicator gives you position size in units, a take-profit level from your reward:risk ratio, and a clear summary on the chart.
Works on any symbol (stocks, forex, crypto, futures). Pine Script v6 · Mozilla Public License 2.0
---
## How to add to your chart
1. In TradingView, open **Indicators** (or search **“Risk Management”** / **“Finpip Risk Manager”**).
2. Select **Risk Management & Position size calculator (FinPip)** and add it to the chart.
3. Open **Settings** (gear on the indicator label) to set your capital, risk %, entry price, and stop-loss price.
---
## What you get
- **Entry, Stop-Loss & Take-Profit** — Drawn as horizontal lines on the chart (direction is Long if Entry > SL, Short if Entry < SL).
- **Position size** — Number of units (shares, lots, contracts) so that if price hits your SL, you lose only your chosen risk amount.
- **Info panel** — Capital, Risk %, Risk $, Reward $, R:R, Size (units), Risk/Unit, Entry/SL/TP prices, and direction. You can move the panel to any corner and change text size.
---
## Settings (inputs)
**Risk & Capital**
- **Total Account Capital ($)** — Capital used for risk (default 10000).
- **Risk per Trade (%)** — % of capital to risk on this trade (default 2.5%).
**Trade Levels**
- **Entry Price** — Your planned or actual entry.
- **Stop-Loss Price** — Exit price if the trade goes against you.
**Profit Target**
- **Reward:Risk Ratio** — Target as multiple of risk (e.g. 4 = 4R). TP is placed at Entry ± (SL distance × R:R).
**Display**
- **Show Info Panel** — On/off for the metrics table.
- **Round to Whole Shares/Units** — On for stocks/shares (whole numbers); off for forex/fractional.
- **Panel Position** — Top Left, Top Right, Bottom Left, Bottom Right.
- **Text Size** — Tiny / Small / Normal / Large.
- **Show Level Labels** — Price labels for Entry, SL, TP on the right.
**Colors** — Customize Entry, SL, TP lines and panel colors.
---
## How it’s calculated
- **Risk $** = Capital × (Risk % ÷ 100)
- **Risk per unit** = |Entry − Stop-Loss|
- **Position size** = Risk $ ÷ Risk per unit (optionally rounded down to whole units)
- **Take-profit** = Entry + (Risk per unit × R:R) for Long, or Entry − (…) for Short
- **Reward $** = Risk $ × R:R
---
## If something looks wrong
- **“Invalid setup — Entry and SL must be different prices”** — Your Entry and Stop-Loss are the same; change one of them.
- **“0 units (rounds to 0)”** — Risk $ is too small for the distance to SL with whole units. Increase capital or risk %, or turn off **Round to Whole Shares/Units** to see fractional size.
---
*Published on TradingView. Open source (MPL 2.0).*
Индикатор

Top 40 Best Performing Nasdaq Stocks with Advanced Stats ScreenWelcome to the CustomQuantLabs Advanced Stats Screener. This dashboard is designed for traders who need more than just price action—it provides a comprehensive, institutional-grade view of the "Top 40" performing assets in the Nasdaq (or any watchlist of your choice) at a single glance.
Instead of flipping through 40 different charts, this screener aggregates Performance Metrics and Advanced Statistical Risk Models into one clean, heatmap-style dashboard. It helps you instantly identify outliers, trend leaders, and potential mean-reversion setups.
Key Features
1. Multi-Timeframe Performance Heatmap Instantly spot momentum. The dashboard tracks returns across 5 key timeframes, color-coded with a dynamic heatmap (Bright Green for leaders, Bright Red for laggards):
Week% (Short-term momentum)
Month% & Quarter% (Medium-term trend)
6M% & 12M% (Long-term secular trend)
2. Institutional Risk Metrics (Advanced Stats) We go beyond simple percentage changes. This screener calculates complex statistical formulas for every single ticker in real-time:
Kelly Criterion (%): A money management formula used to determine optimal position size based on win probability and return ratio. A higher Kelly % suggests a statistically stronger "edge" based on recent history.
Sharpe Ratio: Measures risk-adjusted return. How much return are you getting for every unit of risk? (Values > 1.0 are generally considered good).
Sortino Ratio: Similar to Sharpe, but only penalizes downside volatility. This is crucial for distinguishing between "good volatility" (upside pumps) and "bad volatility" (crashes).
Z-Score: A mean-reversion metric. It measures how many standard deviations the current price is from its 20-day mean.
High Positive Z-Score (>2): Price may be overextended to the upside.
Low Negative Z-Score (<-2): Price may be oversold.
Volatility (%): A dynamic measure of the asset's daily range, helping you gauge the "personality" of the stock before entering.
Customization & Settings
Fully Customizable Watchlist: While pre-loaded with top Nasdaq performers (like NVDA, AMD, PLTR, MU), you can easily edit the "Symbols" input in the settings to track Crypto, Forex, or your own custom stock portfolio.
Smart Theme Detection: Includes a toggle for Dark Mode (ProjectSyndicate style) and Light Mode (Clean white style).
Compact Mode: You can toggle specific columns on or off to fit the table on smaller screens.
How to Use
Add the script to your chart.
Open Settings (Gear Icon).
Paste your list of 40 tickers into the "Ticker List" text area (separated by commas).
Use the Z-Score to find overbought/oversold setups and the Relative Strength (Week/Month) to find breakout candidates.
Disclaimer: This tool is for informational purposes only. The "Top 40" list requires manual updating if the market leaders change. All statistical metrics (Kelly, Sharpe, etc.) are based on historical data and do not guarantee future performance.
Built by CustomQuantLabs. Индикатор

BTC - Satoshis Altcoin Graveyard OVERVIEW
The Satoshi's Altcoin Graveyard (SAG) is a macro-statistical engine designed to solve the problem of Survivorship Bias . It is a well-known phenomenon in the crypto markets that the "Top 10" list is in a constant state of flux. If you look at historical data from CoinMarketCap (CMC) year by year, you will see a revolving door of projects that once seemed "too big to fail" disappearing into obscurity. Meanwhile, Bitcoin has remained the undisputed #1 since inception.
While most traders have a "gut feeling" that Altcoins eventually depreciate against Bitcoin, I believe in measuring it and drawing it on a chart for better visibility. By locking in specific "Cohorts" of market leaders from the past, we can track their inevitable decay through the Satoshi Sieve .
THE 13-COIN STATISTICAL BUCKET
To ensure an objective, non-biased audit, each cohort (we look at 2018, 2020 and 2022) is constructed using a fixed market-cap methodology from the snapshot date (excluding stablecoins):
• The Core: The Top 10 non-stablecoin assets at that time by Marketcap.
• The Risk Alpha: Representative samples from the Top #25, #50, and #100 ranks. (By including lower-ranked "riskier" alts, we capture the full statistical decay of the market, not just the "Blue Chips.")
TECHNICAL ARCHITECTURE
This script is engineered to push the boundaries of the Pine Script engine. TradingView enforces a hard limit of 40 unique data requests . By tracking 3 cohorts of 13 assets plus the Bitcoin base, this indicator utilizes exactly 40/40 requests , providing the maximum possible data density in a single chart window.
THE SPS CONCEPT (Survival Probability Score)
The SPS measures the Breadth of Survival . It answers: "How many coins from this year (the year of the snapshot) are actually outperforming BTC?"
We use a binary logic system to determine if a coin is "Winning" or "Losing" against the only benchmark that matters: Bitcoin.
• The Status Formula: Status = Current_Alt_BTC_Ratio >= Entry_Alt_BTC_Ratio ? 1 : 0 . This means: Every single day, at the Daily Close , the script compares the current Alt/BTC ratio to the fixed ratio from the snapshot date. If the coin is worth more in Bitcoin today than it was back then, it is assigned a "1" (a Win). If it has lost value against Bitcoin, it gets a "0" (a Loss).
• The SPS Line: SPS Line = (Sum of 'Wins' / 13) * 100 This means: We add up all the "Winners" for that specific day and turn it into a percentage. For example, if the Aqua line is at 7.69% on your chart, it confirms that on that day , exactly 1 out of the 13 coins was successfully beating Bitcoin, while the other 12 were underperforming.
THE PERFORMANCE MATRIX
In the top-right corner, we provide a Weighted Portfolio Simulation . This answers the financial question: "If I swapped 1 BTC into an equal-weight basket of these 13 coins on the snapshot day, what is my BTC value today?".
• Value < 1.0 BTC: You lost purchasing power compared to holding Bitcoin.
• Value > 1.0 BTC: You successfully achieved "Alpha" over the benchmark.
HOW TO READ THE CHART
• The Waterfall: Lines generally trend downward as the "Satoshi Sieve" filters out assets that cannot maintain their BTC-relative value.
• Dynamic Winners: We dynamically print the names of the current survivors at the tip of each line. If a cohort shows "None," the graveyard is full.
HOW TO READ THE MATRIX
• The BTC Target: Any portfolio value in the matrix below 1.0 BTC represents a failed altcoin rotation.
• Class of 2018: A portfolio value near 0.15 BTC at the current date, means a 85% loss rate.
• Class of 2020: A portfolio value near 0.77 BTC at the current date, means an approx 20 % loss rate.
• Class of 2022: A portfolio value near 0.31 BTC at the current date, means an approx 70% loss rate.
DIFFERENCE FROM AN ALTCOIN INDEX
Standard Altcoin Indexes (like my ALSI Index ) "rebalance" by removing losers and adding new winners. This is deceptive. The Altcoin Graveyard never rebalances . It forces you to watch the "losers" decay, providing a realistic look at the long-term opportunity cost of "Buy and Hold" for anything other than Bitcoin.
CONCLUSION
The data revealed by the Satoshi Sieve leads to a singular, sobering "Lesson Learned": Picking the right coin to outperform Bitcoin is not just difficult—it is statistically improbable over a long-term horizon.
While the "Risk-Reward" of altcoins is often marketed as having higher upside, the Altcoin Graveyard proves that for the vast majority of assets, the reward does not justify the risk of total portfolio erosion in BTC terms.
• The Mathematical Odds: If you picked a Top 10 coin in 2018, your chance of outperforming BTC today is effectively 0%.
• The Rotation Trap: Most investors "HODL" these assets into the graveyard, hoping for a return to previous ATHs that never comes because the liquidity has already moved on to the next "Class" of winners.
The final conclusion is clear: Diversification into altcoins is often just a slow-motion transfer of wealth back to Bitcoin. If you cannot identify the 1-out-of-13 that survives the Sieve, your best risk-adjusted move has historically been to simply hold the benchmark.
DISCLAIMER
This script is for educational purposes only. It does not constitute financial advice. It is a mathematical study of historical opportunity cost and survivorship bias.
Tags
bitcoin, btc, satoshis graveyard, altseason, dominance, total3, rotation, cycle, index, alsi, Rob Maths, robmaths
Индикатор

Portfolio TrackerDescription
The Portfolio Tracker is a utility dashboard designed for traders who need to monitor the performance of a multi-asset portfolio directly from a single chart layout. While TradingView provides excellent charting for individual symbols, tracking the combined Profit & Loss (PnL) of a basket of 20 different securities (stocks, crypto, forex, or indices) usually requires switching tabs, using external spreadsheets, or logging into multiple exchange accounts.
This script solves that problem by allowing users to manually input their position details into a customizable table. It fetches real-time price data for each symbol and calculates the individual and total portfolio performance, including commission costs.
Why This Tool is Useful
This indicator was built to address specific pain points for active traders:
Consolidated View: Instead of checking 20 different charts to see how your positions are doing, you get a single, real-time snapshot of your entire portfolio's health on one screen.
Risk Management: By seeing the "Total PnL" and "Total Investment" in one place, traders can better understand their overall market exposure, rather than focusing on single winning or losing trades.
Flexible Accounting: The ability to switch between "Unit Price" and "Total Cost" inputs accommodates different trading styles—whether you are a scalper entering a single price or an investor averaging down with a specific total capital allocation.
CRITICAL: Input Logic & Warnings
To ensure accurate PnL calculations, users must understand the relationship between Quantity and Cost, especially when using "Total Cost (Manual)" mode.
The Golden Rule: Your Input Cost must always match the Total Quantity entered.
Example Scenario:
Imagine you buy 2 BTC at a price of $90,000 each.
Correct Entry: You must enter Quantity: 2 and Cost: 180000 ($90k x 2).
Result: If BTC drops to $85k, your Portfolio Value is $170k. The script correctly shows a PnL of -$10,000.
Result: If BTC rises to $95k, your Portfolio Value is $190k. The script correctly shows a PnL of +$10,000.
Incorrect Entry: If you enter Quantity: 2 but leave Cost at 90000 (the unit price).
Result: The script thinks you bought 2 BTC for a total of only $90k. It will instantly show a massive, incorrect profit because the math implies you bought 2 coins for the price of 1.
Please double-check your inputs. The script includes a "Sanity Check" feature to help catch these errors, but accurate data entry is the user's responsibility.
Key Features & Benefits
Multi-Asset Tracking (20 Slots): Monitor up to 20 different tickers simultaneously.
Real-Time Valuation: Uses request.security() to fetch the current market price for every symbol in the list. Your PnL updates with every tick of the market.
Flexible Cost Basis Modes:
Auto-Calc Mode: Enter Entry Price and Quantity. (Best for simple, single-entry trades).
Manual Cost Mode: Enter Total Invested Amount. (Best for averaged-down positions).
Advanced Commission Handling: Supports both Global and Individual commission rates. This provides a realistic "Net PnL" by factoring in fees on both the entry (cost basis) and the theoretical exit (current value).
Input Safety ("Sanity Check"): A logic check that compares the user's input against the current market value. If a user switches to "Total Cost" mode but leaves a small "Unit Price" value in the input field, the script flags the row to prevent irrational PnL percentages (e.g., >100,000%).
Clean & Customizable UI: The table can be positioned in 9 different locations, and inputs are hidden from the chart status line to keep the visual workspace clean.
How It Works
The script operates using a systematic loop that processes user inputs through a series of mathematical validations:
Data Acquisition: The script collects all 20 user inputs and utilizes request.security() to fetch the real-time close price for every non-empty symbol in the list.
Cost Basis Calculation:
In Auto-Calc Mode: The script calculates Raw Cost = Quantity * Input Price.
In Manual Mode: The script takes the Input Value directly as the Raw Cost.
"Round-Trip" Commission Modeling:
Entry Cost: Raw Cost * (1 + Commission%) (Fees increase your breakeven).
Exit Value: (Quantity * Current Price) * (1 - Commission%) (Fees reduce your payout).
Net PnL: Exit Value - Entry Cost.
Sanity Check Algorithm: Before displaying data, the script compares the Input Cost against the Gross Market Value (Qty * Price). If the Input Cost is less than a user-defined threshold (default 1%) of the Market Value, it triggers a warning, assuming the user forgot to update the field to a "Total Cost" figure.
Disclaimer
This script is for informational and educational purposes only. It is a tool to assist in tracking hypothetical or real positions based on manual user inputs and standard TradingView data feeds. It should not be relied upon as a primary accounting ledger or tax reporting tool. Past performance is not indicative of future results. Trading involves risk. Always verify your PnL against your actual exchange or broker statements. Индикатор

Account GuardianAccount Guardian: Dynamic Risk/Reward Overlay
Introduction
Account Guardian is an open-source indicator for TradingView designed to help traders evaluate trade setups before entering positions. It automatically calculates Risk-to-Reward ratios based on market structure, displays visual Stop Loss and Take Profit zones, and provides real-time position sizing recommendations.
The indicator addresses a fundamental question every trader should ask before entering a trade: "Does this setup make mathematical sense?" Account Guardian answers this question visually and numerically, helping traders avoid impulsive entries with poor risk profiles.
Core Functionality
Account Guardian performs four primary functions:
Detects swing highs and swing lows to identify logical stop loss placement levels
Calculates Risk-to-Reward ratios for both long and short setups in real-time
Displays visual SL/TP zones on the chart for immediate trade planning
Computes position sizing based on your account size and risk tolerance
The goal is to provide traders with instant feedback on whether a potential trade meets their minimum risk/reward criteria before committing capital.
How It Works
Swing Detection
The indicator uses pivot point detection to identify recent swing highs and swing lows on the chart. These swing points serve as logical areas for stop loss placement:
For Long Trades: The most recent swing low becomes the stop loss level. Price breaking below this level would invalidate the bullish thesis.
For Short Trades: The most recent swing high becomes the stop loss level. Price breaking above this level would invalidate the bearish thesis.
The swing detection lookback period is configurable, allowing you to adjust sensitivity based on your trading timeframe and style.
It automatically adjusts the tp and sl when it is applied to your chart so it is always moving up and down!
Risk/Reward Calculation
Once swing levels are identified, the indicator calculates:
Entry Price: Current close price (where you would enter)
Stop Loss: Recent swing low (for longs) or swing high (for shorts)
Risk: Distance from entry to stop loss
Take Profit: Entry plus (Risk × Target Multiplier)
R:R Ratio: Reward divided by Risk
The R:R ratio is then evaluated against your configured thresholds to determine if the setup is valid, marginal, or poor.
Visual Elements
SL/TP Zones
When enabled, the indicator draws colored boxes on the chart showing:
Red Zone: Stop Loss area - the region between your entry and stop loss
Green/Gold/Red Zone: Take Profit area - colored based on R:R quality
The color coding provides instant visual feedback:
Green: R:R meets or exceeds your "Good R:R" threshold (default 3:1)
Gold: R:R meets minimum threshold but below "Good" (between 2:1 and 3:1)
Red: R:R below minimum threshold - setup should be avoided
Swing Point Markers
Small circles mark detected swing points on the chart:
Green circles: Swing lows (potential support / long SL levels)
Red circles: Swing highs (potential resistance / short SL levels)
Dashboard Panel
The dashboard in the top-right corner displays comprehensive trade planning information:
R:R Row: Current Risk-to-Reward ratio for long and short setups
Status Row: VALID, OK, BAD, or N/A based on R:R thresholds
Stop Loss Row: Exact price level for stop loss placement
Take Profit Row: Exact price level for take profit placement
Pos Size Row: Recommended position size based on your risk parameters
Risk $ Row: Dollar amount at risk per trade
Position Sizing Logic
The indicator calculates position size using the formula:
Position Size = Risk Amount / Risk per Unit
Where:
Risk Amount = Account Size × (Risk Percentage / 100)
Risk per Unit = Entry Price - Stop Loss Price
For example, with a $10,000 account risking 1% per trade ($100), if your entry is at 100 and stop loss at 98 (risk of 2 per unit), your position size would be 50 units.
Input Parameters
Swing Detection:
Swing Lookback: Number of bars to look back for pivot detection (default: 10). Higher values find more significant swing points but may be slower to update.
Target Multiplier: Multiplier applied to risk to calculate take profit distance (default: 2). A value of 2 means TP is 2× the distance of SL from entry.
Risk/Reward Thresholds:
Minimum R:R: Minimum acceptable Risk-to-Reward ratio (default: 2.0). Setups below this show as "BAD" in red.
Good R:R: Threshold for excellent setups (default: 3.0). Setups at or above this show as "VALID" in green.
Account Settings:
Account Size ($): Your trading account size in dollars (default: 10,000). Used for position sizing calculations.
Risk Per Trade (%): Percentage of account to risk per trade (default: 1.0%). Professional traders typically risk 0.5-2% per trade.
Display:
Show SL/TP Zones: Toggle visibility of the colored zone boxes on chart (default: enabled)
Show Dashboard: Toggle visibility of the information panel (default: enabled)
Analyze Direction: Choose to analyze Long only, Short only, or Both directions (default: Both)
How to Use This Indicator
Basic Workflow:
Add the indicator to your chart
Configure your account size and risk percentage in the settings
Set your minimum and good R:R thresholds based on your trading rules
Look at the dashboard to see current R:R for potential long and short entries
Only consider trades where the status shows "VALID" or at minimum "OK"
Use the displayed SL and TP levels for your order placement
Use the position size recommendation to determine lot/contract size
Interpreting the Dashboard:
VALID (Green): Excellent setup - R:R meets your "Good" threshold. This is the ideal scenario for taking a trade.
OK (Gold): Acceptable setup - R:R meets minimum but isn't optimal. Consider taking if other confluence factors align.
BAD (Red): Poor setup - R:R below minimum threshold. Avoid this trade or wait for better entry.
N/A (Gray): Cannot calculate - usually means no valid swing point detected yet.
Best Practices:
Use this indicator as a filter, not a signal generator. It tells you IF a trade makes sense, not WHEN to enter.
Combine with your existing entry strategy - use Account Guardian to validate setups from other analysis.
Adjust the swing lookback based on your timeframe. Lower timeframes may need smaller lookback values.
Be honest with your account size input - accurate position sizing requires accurate inputs.
Consider the target multiplier carefully. Higher multipliers mean larger potential reward but lower probability of hitting TP.
Alerts
The indicator includes four alert conditions:
Good Long Setup: Triggers when long R:R reaches or exceeds your "Good R:R" threshold
Good Short Setup: Triggers when short R:R reaches or exceeds your "Good R:R" threshold
Bad Long Setup: Triggers when long R:R falls below your minimum threshold
Bad Short Setup: Triggers when short R:R falls below your minimum threshold
These alerts can help you monitor multiple charts and get notified when favorable setups appear.
Technical Implementation
The indicator is built using Pine Script v6 and includes:
Pivot-based swing detection using ta.pivothigh() and ta.pivotlow()
Dynamic box drawing for visual SL/TP zones
Table-based dashboard for clean information display
Color-coded visual feedback system
Persistent variable tracking for swing levels
Code Structure:
// Swing Detection
float swingHi = ta.pivothigh(high, swingLen, swingLen)
float swingLo = ta.pivotlow(low, swingLen, swingLen)
// R:R Calculation for Long
float longSL = recentSwingLo
float longRisk = entry - longSL
float longTP = entry + (longRisk * targetMult)
float longRR = (longTP - entry) / longRisk
// Position Sizing
float riskAmount = accountSize * (riskPct / 100)
float posSize = riskAmount / longRisk
Limitations
The indicator uses historical swing points which may not always represent optimal SL placement for your specific strategy
Position sizing assumes you can trade fractional units - adjust accordingly for instruments with minimum lot sizes
R:R calculations assume linear price movement and don't account for gaps or slippage
The indicator doesn't predict price direction - it only evaluates the mathematical viability of a setup
Swing detection has inherent lag due to the lookback period required for pivot confirmation
Recommended Settings by Trading Style
Scalping (1-5 minute charts):
Swing Lookback: 5-8
Target Multiplier: 1-2
Minimum R:R: 1.5
Good R:R: 2.0
Day Trading (15-60 minute charts):
Swing Lookback: 8-12
Target Multiplier: 2
Minimum R:R: 2.0
Good R:R: 3.0
Swing Trading (4H-Daily charts):
Swing Lookback: 10-20
Target Multiplier: 2-3
Minimum R:R: 2.5
Good R:R: 4.0
Why Risk/Reward Matters
Many traders focus solely on win rate, but profitability depends on the combination of win rate AND risk/reward ratio. Consider these scenarios:
50% win rate with 1:1 R:R = Breakeven (before costs)
50% win rate with 2:1 R:R = Profitable
40% win rate with 3:1 R:R = Profitable
60% win rate with 1:2 R:R = Losing money
Account Guardian helps ensure you only take trades where the math works in your favor, even if you're wrong more often than you're right.
Disclaimer
This indicator is provided for educational and informational purposes only. It is not intended as financial, investment, trading, or any other type of advice or recommendation.
Trading involves substantial risk of loss and is not suitable for all investors. The calculations provided by this indicator are based on historical price data and mathematical formulas that may not accurately predict future price movements.
Position sizing recommendations are estimates based on user inputs and should be verified before placing actual trades. Always consider factors such as leverage, margin requirements, and broker-specific rules when determining actual position sizes.
The Risk-to-Reward ratios displayed are theoretical calculations based on swing point detection. Actual trade outcomes will vary based on market conditions, execution quality, and other factors not captured by this indicator.
Past performance does not guarantee future results. Users should thoroughly test any trading approach in a demo environment before risking real capital. The authors and publishers of this indicator are not responsible for any losses or damages arising from its use.
Always consult with a qualified financial advisor before making investment decisions.
Индикатор

Volatility Targeting: Single Asset [BackQuant]Volatility Targeting: Single Asset
An educational example that demonstrates how volatility targeting can scale exposure up or down on one symbol, then applies a simple EMA cross for long or short direction and a higher timeframe style regime filter to gate risk. It builds a synthetic equity curve and compares it to buy and hold and a benchmark.
Important disclaimer
This script is a concept and education example only . It is not a complete trading system and it is not meant for live execution. It does not model many real world constraints, and its equity curve is only a simplified simulation. If you want to trade any idea like this, you need a proper strategy() implementation, realistic execution assumptions, and robust backtesting with out of sample validation.
Single asset vs the full portfolio concept
This indicator is the single asset, long short version of the broader volatility targeted momentum portfolio concept. The original multi asset concept and full portfolio implementation is here:
That portfolio script is about allocating across multiple assets with a portfolio view. This script is intentionally simpler and focuses on one symbol so you can clearly see how volatility targeting behaves, how the scaling interacts with trend direction, and what an equity curve comparison looks like.
What this indicator is trying to demonstrate
Volatility targeting is a risk scaling framework. The core idea is simple:
If realized volatility is low relative to a target, you can scale position size up so the strategy behaves like it has a stable risk budget.
If realized volatility is high relative to a target, you scale down to avoid getting blown around by the market.
Instead of always being 1x long or 1x short, exposure becomes dynamic. This is often used in risk parity style systems, trend following overlays, and volatility controlled products.
This script combines that risk scaling with a simple trend direction model:
Fast and slow EMA cross determines whether the strategy is long or short.
A second, longer EMA cross acts as a regime filter that decides whether the system is ACTIVE or effectively in CASH.
An equity curve is built from the scaled returns so you can visualize how the framework behaves across regimes.
How the logic works step by step
1) Returns and simple momentum
The script uses log returns for the base return stream:
ret = log(price / price )
It also computes a simple momentum value:
mom = price / price - 1
In this version, momentum is mainly informational since the directional signal is the EMA cross. The lookback input is shared with volatility estimation to keep the concept compact.
2) Realized volatility estimation
Realized volatility is estimated as the standard deviation of returns over the lookback window, then annualized:
vol = stdev(ret, lookback) * sqrt(tradingdays)
The Trading Days/Year input controls annualization:
252 is typical for traditional markets.
365 is typical for crypto since it trades daily.
3) Volatility targeting multiplier
Once realized vol is estimated, the script computes a scaling factor that tries to push realized volatility toward the target:
volMult = targetVol / vol
This is then clamped into a reasonable range:
Minimum 0.1 so exposure never goes to zero just because vol spikes.
Maximum 5.0 so exposure is not allowed to lever infinitely during ultra low volatility periods.
This clamp is one of the most important “sanity rails” in any volatility targeted system. Without it, very low volatility regimes can create unrealistic leverage.
4) Scaled return stream
The per bar return used for the equity curve is the raw return multiplied by the volatility multiplier:
sr = ret * volMult
Think of this as the return you would have earned if you scaled exposure to match the volatility budget.
5) Long short direction via EMA cross
Direction is determined by a fast and slow EMA cross on price:
If fast EMA is above slow EMA, direction is long.
If fast EMA is below slow EMA, direction is short.
This produces dir as either +1 or -1. The scaled return stream is then signed by direction:
avgRet = dir * sr
So the strategy return is volatility targeted and directionally flipped depending on trend.
6) Regime filter: ACTIVE vs CASH
A second EMA pair acts as a top level regime filter:
If fast regime EMA is above slow regime EMA, the system is ACTIVE.
If fast regime EMA is below slow regime EMA, the system is considered CASH, meaning it does not compound equity.
This is designed to reduce participation in long bear phases or low quality environments, depending on how you set the regime lengths. By default it is a classic 50 and 200 EMA cross structure.
Important detail, the script applies regime_filter when compounding equity, meaning it uses the prior bar regime state to avoid ambiguous same bar updates.
7) Equity curve construction
The script builds a synthetic equity curve starting from Initial Capital after Start Date . Each bar:
If regime was ACTIVE on the previous bar, equity compounds by (1 + netRet).
If regime was CASH, equity stays flat.
Fees are modeled very simply as a per bar penalty on returns:
netRet = avgRet - (fee_rate * avgRet)
This is not realistic execution modeling, it is just a simple turnover penalty knob to show how friction can reduce compounded performance. Real backtesting should model trade based costs, spreads, funding, and slippage.
Benchmark and buy and hold comparison
The script pulls a benchmark symbol via request.security and builds a buy and hold equity curve starting from the same date and initial capital. The buy and hold curve is based on benchmark price appreciation, not the strategy’s asset price, so you can compare:
Strategy equity on the chart symbol.
Buy and hold equity for the selected benchmark instrument.
By default the benchmark is TVC:SPX, but you can set it to anything, for crypto you might set it to BTC, or a sector index, or a dominance proxy depending on your study.
What it plots
If enabled, the indicator plots:
Strategy Equity as a line, colored by recent direction of equity change, using Positive Equity Color and Negative Equity Color .
Buy and Hold Equity for the chosen benchmark as a line.
Optional labels that tag each curve on the right side of the chart.
This makes it easy to visually see when volatility targeting and regime gating change the shape of the equity curve relative to a simple passive hold.
Metrics table explained
If Show Metrics Table is enabled, a table is built and populated with common performance statistics based on the simulated daily returns of the strategy equity curve after the start date. These include:
Net Profit (%) total return relative to initial capital.
Max DD (%) maximum drawdown computed from equity peaks, stored over time.
Win Rate percent of positive return bars.
Annual Mean Returns (% p/y) mean daily return annualized.
Annual Stdev Returns (% p/y) volatility of daily returns annualized.
Variance of annualized returns.
Sortino Ratio annualized return divided by downside deviation, using negative return stdev.
Sharpe Ratio risk adjusted return using the risk free rate input.
Omega Ratio positive return sum divided by negative return sum.
Gain to Pain total return sum divided by absolute loss sum.
CAGR (% p/y) compounded annual growth rate based on time since start date.
Portfolio Alpha (% p/y) alpha versus benchmark using beta and the benchmark mean.
Portfolio Beta covariance of strategy returns with benchmark returns divided by benchmark variance.
Skewness of Returns actually the script computes a conditional value based on the lower 5 percent tail of returns, so it behaves more like a simple CVaR style tail loss estimate than classic skewness.
Important note, these are calculated from the synthetic equity stream in an indicator context. They are useful for concept exploration, but they are not a substitute for professional backtesting where trade timing, fills, funding, and leverage constraints are accurately represented.
How to interpret the system conceptually
Vol targeting effect
When volatility rises, volMult falls, so the strategy de risks and the equity curve typically becomes smoother. When volatility compresses, volMult rises, so the system takes more exposure and tries to maintain a stable risk budget.
This is why volatility targeting is often used as a “risk equalizer”, it can reduce the “biggest drawdowns happen only because vol expanded” problem, at the cost of potentially under participating in explosive upside if volatility rises during a trend.
Long short directional effect
Because direction is an EMA cross:
In strong trends, the direction stays stable and the scaled return stream compounds in that trend direction.
In choppy ranges, the EMA cross can flip and create whipsaws, which is where fees and regime filtering matter most.
Regime filter effect
The 50 and 200 style filter tries to:
Keep the system active in sustained up regimes.
Reduce exposure during long down regimes or extended weakness.
It will always be late at turning points, by design. It is a slow filter meant to reduce deep participation, not to catch bottoms.
Common applications
This script is mainly for understanding and research, but conceptually, volatility targeting overlays are used for:
Risk budgeting normalize risk so your exposure is not accidentally huge in high vol regimes.
System comparison see how a simple trend model behaves with and without vol scaling.
Parameter exploration test how target volatility, lookback length, and regime lengths change the shape of equity and drawdowns.
Framework building as a reference blueprint before implementing a proper strategy() version with trade based execution logic.
Tuning guidance
Lookback lower values react faster to vol shifts but can create unstable scaling, higher values smooth scaling but react slower to regime changes.
Target volatility higher targets increase exposure and drawdown potential, lower targets reduce exposure and usually lower drawdowns, but can under perform in strong trends.
Signal EMAs tighter EMAs increase trade frequency, wider EMAs reduce churn but react slower.
Regime EMAs slower regime filters reduce false toggles but will miss early trend transitions.
Fees if you crank this up you will see how sensitive higher turnover parameter sets are to friction.
Final note
This is a compact educational demonstration of a volatility targeted, long short single asset framework with a regime gate and a synthetic equity curve. If you want a production ready implementation, the correct next step is to convert this concept into a strategy() script, add realistic execution and cost modeling, test across multiple timeframes and market regimes, and validate out of sample before making any decision based on the results.
Индикатор

DCA Ladder CalculatorThis script is a DCA (Dollar-Cost Averaging) Ladder Calculator with Risk & Leverage Management baked in.
It’s designed for both LONG and SHORT positions, and helps you:
🎯 Strategically scale into positions across multiple entry points
🔐 Control risk exposure via defined capital allocation
⚖️ Utilize leverage responsibly — for efficiency, not destruction
🧮 Visualize risk, stop loss level, and entry distribution
🔁 Adapt to trend reversals or key zones, especially when combined with reversal indicators or higher timeframe signals
🧠 How It Works
This tool takes a capital allocation approach to building a ladder of positions:
1. You define:
- Portfolio value
- Risk per trade (as %)
- Leverage
- Number of DCA levels
- Entry multiplier (e.g. 1x, 2x, 4x...)
2. The script then:
- Calculates total margin to risk = Portfolio × Risk %
- Calculates total leveraged position size = Margin × Leverage
- Distributes entries according to exponential weights (1x, 2x, 4x...), totaling 7 for 3 levels
- Calculates per-entry:
- Entry price (based on price zone spacing)
- Multiplier
- Exact margin per entry
- Leverage per entry (margin × leverage)
- Computes:
- Average entry price (margin-weighted)
- Approximate stop loss level based on recent ATR and price structure
- % drawdown to SL
- Total margin and position size
3. Displays all this in a clean on-chart table.
📈 How to Use It
1. Apply the indicator to a chart (default: 1D — ideal for clean zones).
2. Configure your:
- Portfolio Value (total trading capital)
- Risk per Trade (%) (your acceptable loss)
- Leverage (exchange or strategy-based)
- DCA Levels (e.g. 3 = anchor + 2 entries)
- Multiplier (typically 2.0 for doubling)
3. Choose LONG or SHORT mode depending on direction.
4. The table will show:
- Entry price ladder
- Margin used per entry
- Total position size
- Approx. stop loss (where your full risk is defined)
Use in conjunction with price action, S/R zones, trendline breaks, volume divergence, or reversal indicators.
✅ Best Practices for Using This Tool
- Leverage is a tool, not a weapon. Use it to scale smartly — not recklessly.
- Use fewer, higher-conviction entries. Don’t blindly ladder; combine with price structure and signals.
- Stick to your risk percent. Never risk more than you can afford to lose. Let this calculator enforce discipline.
- Combine with other confirmation tools, like RSI divergence, momentum shifts, OB zones, etc.
- Avoid martingale-style over-exposure. This is not a gambling tool — it’s for capital efficiency.
🛡️ What This Tool Does NOT Do
- This is not a trade signal indicator.
- It does not place trades or auto-manage positions.
- It does not replace personal responsibility or strategy — it's a tool to help apply structure.
⚠️ Disclaimer
This script is for educational and informational purposes only.
It does not constitute financial advice, nor is it a recommendation to buy or sell any financial instrument.
Always consult a licensed financial advisor before making investment decisions.
Use of leverage involves high risk and can lead to substantial losses.
The author and publisher assume no liability for any trading losses resulting from use of this script. Индикатор

Volatility-Targeted Momentum Portfolio [BackQuant]Volatility-Targeted Momentum Portfolio
A complete momentum portfolio engine that ranks assets, targets a user-defined volatility, builds long, short, or delta-neutral books, and reports performance with metrics, attribution, Monte Carlo scenarios, allocation pie, and efficiency scatter plots. This description explains the theory and the mechanics so you can configure, validate, and deploy it with intent.
Table of contents
What the script does at a glance
Momentum, what it is, how to know if it is present
Volatility targeting, why and how it is done here
Portfolio construction modes: Long Only, Short Only, Delta Neutral
Regime filter and when the strategy goes to cash
Transaction cost modelling in this script
Backtest metrics and definitions
Performance attribution chart
Monte Carlo simulation
Scatter plot analysis modes
Asset allocation pie chart
Inputs, presets, and deployment checklist
Suggested workflow
1) What the script does at a glance
Pulls a list of up to 15 tickers, computes a simple momentum score on each over a configurable lookback, then volatility-scales their bar-to-bar return stream to a target annualized volatility.
Ranks assets by raw momentum, selects the top 3 and bottom 3, builds positions according to the chosen mode, and gates exposure with a fast regime filter.
Accumulates a portfolio equity curve with risk and performance metrics, optional benchmark buy-and-hold for comparison, and a full alert suite.
Adds visual diagnostics: performance attribution bars, Monte Carlo forward paths, an allocation pie, and scatter plots for risk-return and factor views.
2) Momentum: definition, detection, and validation
Momentum is the tendency of assets that have performed well to continue to perform well, and of underperformers to continue underperforming, over a specific horizon. You operationalize it by selecting a horizon, defining a signal, ranking assets, and trading the leaders versus laggards subject to risk constraints.
Signal choices . Common signals include cumulative return over a lookback window, regression slope on log-price, or normalized rate-of-change. This script uses cumulative return over lookback bars for ranking (variable cr = price/price - 1). It keeps the ranking simple and lets volatility targeting handle risk normalization.
How to know momentum is present .
Leaders and laggards persist across adjacent windows rather than flipping every bar.
Spread between average momentum of leaders and laggards is materially positive in sample.
Cross-sectional dispersion is non-trivial. If everything is flat or highly correlated with no separation, momentum selection will be weak.
Your validation should include a diagnostic that measures whether returns are explained by a momentum regression on the timeseries.
Recommended diagnostic tool . Before running any momentum portfolio, verify that a timeseries exhibits stable directional drift. Use this indicator as a pre-check: It fits a regression to price, exposes slope and goodness-of-fit style context, and helps confirm if there is usable momentum before you force a ranking into a flat regime.
3) Volatility targeting: purpose and implementation here
Purpose . Volatility targeting seeks a more stable risk footprint. High-vol assets get sized down, low-vol assets get sized up, so each contributes more evenly to total risk.
Computation in this script (per asset, rolling):
Return series ret = log(price/price ).
Annualized volatility estimate vol = stdev(ret, lookback) * sqrt(tradingdays).
Leverage multiplier volMult = clamp(targetVol / vol, 0.1, 5.0).
This caps sizing so extremely low-vol assets don’t explode weight and extremely high-vol assets don’t go to zero.
Scaled return stream sr = ret * volMult. This is the per-bar, risk-adjusted building block used in the portfolio combinations.
Interpretation . You are not levering your account on the exchange, you are rescaling the contribution each asset’s daily move has on the modeled equity. In live trading you would reflect this with position sizing or notional exposure.
4) Portfolio construction modes
Cross-sectional ranking . Assets are sorted by cr over the chosen lookback. Top and bottom indices are extracted without ties.
Long Only . Averages the volatility-scaled returns of the top 3 assets: avgRet = mean(sr_top1, sr_top2, sr_top3). Position table shows per-asset leverages and weights proportional to their current volMult.
Short Only . Averages the negative of the volatility-scaled returns of the bottom 3: avgRet = mean(-sr_bot1, -sr_bot2, -sr_bot3). Position table shows short legs.
Delta Neutral . Long the top 3 and short the bottom 3 in equal book sizes. Each side is sized to 50 percent notional internally, with weights within each side proportional to volMult. The return stream mixes the two sides: avgRet = mean(sr_top1,sr_top2,sr_top3, -sr_bot1,-sr_bot2,-sr_bot3).
Notes .
The selection metric is raw momentum, the execution stream is volatility-scaled returns. This separation is deliberate. It avoids letting volatility dominate ranking while still enforcing risk parity at the return contribution stage.
If everything rallies together and dispersion collapses, Long Only may behave like a single beta. Delta Neutral is designed to extract cross-sectional momentum with low net beta.
5) Regime filter
A fast EMA(12) vs EMA(21) filter gates exposure.
Long Only active when EMA12 > EMA21. Otherwise the book is set to cash.
Short Only active when EMA12 < EMA21. Otherwise cash.
Delta Neutral is always active.
This prevents taking long momentum entries during obvious local downtrends and vice versa for shorts. When the filter is false, equity is held flat for that bar.
6) Transaction cost modelling
There are two cost touchpoints in the script.
Per-bar drag . When the regime filter is active, the per-bar return is reduced by fee_rate * avgRet inside netRet = avgRet - (fee_rate * avgRet). This models proportional friction relative to traded impact on that bar.
Turnover-linked fee . The script tracks changes in membership of the top and bottom baskets (top1..top3, bot1..bot3). The intent is to charge fees when composition changes. The template counts changes and scales a fee by change count divided by 6 for the six slots.
Use case: increase fee_rate to reflect taker fees and slippage if you rebalance every bar or trade illiquid assets. Reduce it if you rebalance less often or use maker orders.
Practical advice .
If you rebalance daily, start with 5–20 bps round-trip per switch on liquid futures and adjust per venue.
For crypto perp microcaps, stress higher cost assumptions and add slippage buffers.
If you only rotate on lookback boundaries or at signals, use alert-driven rebalances and lower per-bar drag.
7) Backtest metrics and definitions
The script computes a standard set of portfolio statistics once the start date is reached.
Net Profit percent over the full test.
Max Drawdown percent, tracked from running peaks.
Annualized Mean and Stdev using the chosen trading day count.
Variance is the square of annualized stdev.
Sharpe uses daily mean adjusted by risk-free rate and annualized.
Sortino uses downside stdev only.
Omega ratio of sum of gains to sum of losses.
Gain-to-Pain total gains divided by total losses absolute.
CAGR compounded annual growth from start date to now.
Alpha, Beta versus a user-selected benchmark. Beta from covariance of daily returns, Alpha from CAPM.
Skewness of daily returns.
VaR 95 linear-interpolated 5th percentile of daily returns.
CVaR average of the worst 5 percent of daily returns.
Benchmark Buy-and-Hold equity path for comparison.
8) Performance attribution
Cumulative contribution per asset, adjusted for whether it was held long or short and for its volatility multiplier, aggregated across the backtest. You can filter to winners only or show both sides. The panel is sorted by contribution and includes percent labels.
9) Monte Carlo simulation
The panel draws forward equity paths from either a Normal model parameterized by recent mean and stdev, or non-parametric bootstrap of recent daily returns. You control the sample length, number of simulations, forecast horizon, visibility of individual paths, confidence bands, and a reproducible seed.
Normal uses Box-Muller with your seed. Good for quick, smooth envelopes.
Bootstrap resamples realized returns, preserving fat tails and volatility clustering better than a Gaussian assumption.
Bands show 10th, 25th, 75th, 90th percentiles and the path mean.
10) Scatter plot analysis
Four point-cloud modes, each plotting all assets and a star for the current portfolio position, with quadrant guides and labels.
Risk-Return Efficiency . X is risk proxy from leverage, Y is expected return from annualized momentum. The star shows the current book’s composite.
Momentum vs Volatility . Visualizes whether leaders are also high vol, a cue for turnover and cost expectations.
Beta vs Alpha . X is a beta proxy, Y is risk-adjusted excess return proxy. Useful to see if leaders are just beta.
Leverage vs Momentum . X is volMult, Y is momentum. Shows how volatility targeting is redistributing risk.
11) Asset allocation pie chart
Builds a wheel of current allocations.
Long Only, weights are proportional to each long asset’s current volMult and sum to 100 percent.
Short Only, weights show the short book as positive slices that sum to 100 percent.
Delta Neutral, 50 percent long and 50 percent short books, each side leverage-proportional.
Labels can show asset, percent, and current leverage.
12) Inputs and quick presets
Core
Portfolio Strategy . Long Only, Short Only, Delta Neutral.
Initial Capital . For equity scaling in the panel.
Trading Days/Year . 252 for stocks, 365 for crypto.
Target Volatility . Annualized, drives volMult.
Transaction Fees . Per-bar drag and composition change penalty, see the modelling notes above.
Momentum Lookback . Ranking horizon. Shorter is more reactive, longer is steadier.
Start Date . Ensure every symbol has data back to this date to avoid bias.
Benchmark . Used for alpha, beta, and B&H line.
Diagnostics
Metrics, Equity, B&H, Curve labels, Daily return line, Rolling drawdown fill.
Attribution panel. Toggle winners only to focus on what matters.
Monte Carlo mode with Normal or Bootstrap and confidence bands.
Scatter plot type and styling, labels, and portfolio star.
Pie chart and labels for current allocation.
Presets
Crypto Daily, Long Only . Lookback 25, Target Vol 50 percent, Fees 10 bps, Regime filter on, Metrics and Drawdown on. Monte Carlo Bootstrap with Recent 200 bars for bands.
Crypto Daily, Delta Neutral . Lookback 25, Target Vol 50 percent, Fees 15–25 bps, Regime filter always active for this mode. Use Scatter Risk-Return to monitor efficiency and keep the star near upper left quadrants without drifting rightward.
Equities Daily, Long Only . Lookback 60–120, Target Vol 15–20 percent, Fees 5–10 bps, Regime filter on. Use Benchmark SPX and watch Alpha and Beta to keep the book from becoming index beta.
13) Suggested workflow
Universe sanity check . Pick liquid tickers with stable data. Thin assets distort vol estimates and fees.
Check momentum existence . Run on your timeframe. If slope and fit are weak, widen lookback or avoid that asset or timeframe.
Set risk budget . Choose a target volatility that matches your drawdown tolerance. Higher target increases turnover and cost sensitivity.
Pick mode . Long Only for bull regimes, Short Only for sustained downtrends, Delta Neutral for cross-sectional harvesting when index direction is unclear.
Tune lookback . If leaders rotate too often, lengthen it. If entries lag, shorten it.
Validate cost assumptions . Increase fee_rate and stress Monte Carlo. If the edge vanishes with modest friction, refine selection or lengthen rebalance cadence.
Run attribution . Confirm the strategy’s winners align with intuition and not one unstable outlier.
Use alerts . Enable position change, drawdown, volatility breach, regime, momentum shift, and crash alerts to supervise live runs.
Important implementation details mapped to code
Momentum measure . cr = price / price - 1 per symbol for ranking. Simplicity helps avoid overfitting.
Volatility targeting . vol = stdev(log returns, lookback) * sqrt(tradingdays), volMult = clamp(targetVol / vol, 0.1, 5), sr = ret * volMult.
Selection . Extract indices for top1..top3 and bot1..bot3. The arrays rets, scRets, lev_vals, and ticks_arr track momentum, scaled returns, leverage multipliers, and display tickers respectively.
Regime filter . EMA12 vs EMA21 switch determines if the strategy takes risk for Long or Short modes. Delta Neutral ignores the gate.
Equity update . Equity multiplies by 1 + netRet only when the regime was active in the prior bar. Buy-and-hold benchmark is computed separately for comparison.
Tables . Position tables show current top or bottom assets with leverage and weights. Metric table prints all risk and performance figures.
Visualization panels . Attribution, Monte Carlo, scatter, and pie use the last bars to draw overlays that update as the backtest proceeds.
Final notes
Momentum is a portfolio effect. The edge comes from cross-sectional dispersion, adequate risk normalization, and disciplined turnover control, not from a single best asset call.
Volatility targeting stabilizes path but does not fix selection. Use the momentum regression link above to confirm structure exists before you size into it.
Always test higher lag costs and slippage, then recheck metrics, attribution, and Monte Carlo envelopes. If the edge persists under stress, you have something robust.
Индикатор

Crypto Index Price# Crypto Index Price - Indicator Description
## 📊 What is this indicator?
**Crypto Index Price** is an indicator for creating your own cryptocurrency index based on an equal-weighted portfolio. It allows you to track the overall dynamics of the cryptocurrency market through a composite index of selected assets.
## 🎯 Key Features
- **Up to 20 assets in the index** — create an index from any trading pairs
- **Equal-weighted methodology** — each asset has the same weight in the index
- **Moving average** — optional trend filter for the index
- **Flexible visualization settings** — customizable colors and line thickness
## 📈 How to Use
The indicator is displayed in a separate pane below the chart and shows:
1. **Blue line** — crypto index value
2. **Orange line** (optional) — moving average of the index
### Trading Applications:
- **Identify overall market trend** — if the index is rising, most coins are in an uptrend
- **Divergences** — divergence between your asset and the index may signal local opportunities
- **Signal confirmation** — use the index to confirm trading decisions on individual coins
- **Market condition filter** — trade longs when index is above MA, shorts when below
## ⚙️ Settings
### Assets (Symbols)
- **Asset 1-10** — main cryptocurrencies (default: BTC, ETH, BNB, SOL, XRP, ADA, AVAX, LINK, DOGE, TRX)
- **Asset 11-20** — additional slots for index expansion
### Visual Parameters
- **Index line color** — main line color (default: blue)
- **Line width** — from 1 to 5 pixels
- **Show moving average** — enable/disable MA
- **MA period** — moving average calculation period (default: 20)
- **MA color** — moving average line color (default: orange)
## 💡 Recommendations
- For a top coins index, use 5-10 largest cryptocurrencies by market cap
- For an altcoin index, add medium and small coins from your sector
- Use MA to filter false signals and identify the global trend
- Compare individual asset behavior with the index to find anomalies
## ⚠️ Important
The indicator uses equal-weighted methodology — each coin contributes equally regardless of price or market cap. This differs from cap-weighted indices and may provide a different market perspective.
---
*This indicator is intended for analysis and is not trading advice. Always conduct your own analysis before making trading decisions.*
--- Индикатор

Portfolio Strategy TesterThe Portfolio Strategy Tester is an institutional-grade backtesting framework that evaluates the performance of trend-following strategies on multi-asset portfolios. It enables users to construct custom portfolios of up to 30 assets and apply moving average crossover strategies across individual holdings. The model features a clear, color-coded table that provides a side-by-side comparison between the buy-and-hold portfolio and the portfolio using the risk management strategy, offering a comprehensive assessment of both approaches relative to the benchmark.
Portfolios are constructed by entering each ticker symbol in the menu, assigning its respective weight, and reviewing the total sum of individual weights displayed at the top left of the table. For strategy selection, users can choose between Exponential Moving Average (EMA), Simple Moving Average (SMA), Wilder’s Moving Average (RMA), Weighted Moving Average (WMA), Moving Average Convergence Divergence (MACD), and Volume-Weighted Moving Average (VWMA). Moving average lengths are defined in the menu and apply only to strategy-enabled assets.
To accurately replicate real-world portfolio conditions, users can choose between daily, weekly, monthly, or quarterly rebalancing frequencies and decide whether cash is held or redistributed. Daily rebalancing maintains constant portfolio weights, while longer intervals allow natural drift. When cash positions are not allowed, capital from bearish assets is automatically redistributed proportionally among bullish assets, ensuring the portfolio remains fully invested at all times. The table displays a comprehensive set of widely used institutional-grade performance metrics:
CAGR = Compounded annual growth rate of returns.
Volatility = Annualized standard deviation of returns.
Sharpe = CAGR per unit of annualized standard deviation.
Sortino = CAGR per unit of annualized downside deviation.
Calmar = CAGR relative to maximum drawdown.
Max DD = Largest peak-to-trough decline in value.
Beta (β) = Sensitivity of returns relative to benchmark returns.
Alpha (α) = Excess annualized risk-adjusted returns relative to benchmark.
Upside = Ratio of average return to benchmark return on up days.
Downside = Ratio of average return to benchmark return on down days.
Tracking = Annualized standard deviation of returns versus benchmark.
Turnover = Average sum of absolute changes in weights per year.
Cumulative returns are displayed on each label as the total percentage gain from the selected start date, with green indicating positive returns and red indicating negative returns. In the table, baseline metrics serve as the benchmark reference and are always gray. For portfolio metrics, green indicates outperformance relative to the baseline, while red indicates underperformance relative to the baseline. For strategy metrics, green indicates outperformance relative to both the baseline and the portfolio, red indicates underperformance relative to both, and gray indicates underperformance relative to either the baseline or portfolio. Metrics such as Volatility, Tracking Error, and Turnover ratio are always displayed in gray as they serve as descriptive measures.
In summary, the Portfolio Strategy Tester is a comprehensive backtesting tool designed to help investors evaluate different trend-following strategies on custom portfolios. It enables real-world simulation of both active and passive investment approaches and provides a full set of standard institutional-grade performance metrics to support data-driven comparisons. While results are based on historical performance, the model serves as a powerful portfolio management and research framework for developing, validating, and refining systematic investment strategies. Индикатор

Portfolio Simulator & BacktesterMulti-asset portfolio simulator with different metrics and ratios, DCA modeling, and rebalancing strategies.
Core Features
Portfolio Construction
Up to 5 assets with customizable weights (must total 100%)
Support for any tradable symbol: stocks, ETFs, crypto, indices, commodities
Real-time validation of allocations
Dollar Cost Averaging
Monthly or Quarterly contributions
Applies to both portfolio and benchmark for fair comparison
Model real-world investing behavior
Rebalancing
Four strategies: None, Monthly, Quarterly, Yearly
Automatic rebalancing to target weights
Transaction cost modeling (customizable fee %)
Key Metrics Table
CAGR: Annualized compound return (S&P 500 avg: ~10%)
Alpha: Excess return vs. benchmark (positive = outperformance)
Sharpe Ratio: Return per unit of risk (>1.0 is good, >2.0 excellent)
Sortino Ratio: Like Sharpe but only penalizes downside (better metric)
Calmar Ratio: CAGR / Max Drawdown (>1.0 good, >2.0 excellent)
Max Drawdown: Largest peak-to-trough decline
Win Rate: % of positive days (doesn't indicate profitability)
Visualization
Dual-chart comparison - Portfolio vs. Benchmark
Dollar or percentage view toggle
Customizable colors and line width
Two tables: Statistics + Asset Allocation
Adjustable table position and text size
🚀 Quick Start Guide
Enter 1-5 ticker symbols (e.g., SPY, QQQ, TLT, GLD, BTCUSD)
Make sure percentage weights total 100%
Choose date range (ensure chart shows full period - zoom out!)
Configure DCA and rebalancing (optional)
Select benchmark (default: SPX)
Analyze results in statistics table
💡 Pro Tips
Chart data matters: Load SPY or your longest-history asset as main chart
If you select an asset that was not available for the selected period, the chart will not show up! E.g. BTCUSD data: Only available from ~2017 onwards.
Transaction fees: 0.1% default (adjust to match your broker)
⚠️ Important Notes
Requires visible chart data (zoom out to show full date range)
Limited by each asset's historical data availability
Transaction fees and costs are modeled, but taxes/slippage are not
Past performance ≠ future results
Use for research and education only, not financial advice
Let me know if you have any suggestions to improve this simulator. Индикатор

Normalized Portfolio TrackerThis script lets you create, visualize, and track a custom portfolio of up to 15 assets directly on TradingView.
It calculates a synthetic "portfolio index" by combining multiple tickers with user-defined weights, automatically normalizing them so the total allocation always equals 100%.
All assets are scaled to a common starting point, allowing you to compare your portfolio’s performance versus any benchmark like SPY, QQQ, or BTC.
🚀 Goal
This script helps traders and investors:
• Understand the combined performance of their portfolio.
• Normalize diverse assets into a single synthetic chart .
• Make portfolio-level insights without relying on external spreadsheets.
🎯 Use Cases
• Backtest your portfolio allocations directly on the chart.
• Compare your portfolio vs. benchmarks like SPY, QQQ, BTC.
• Track thematic baskets (commodities, EV supply chain, regional ETFs).
• Visualize how each component contributes to overall performance.
📊 Features
• Weighted Portfolio Performance : Combines selected assets into a synthetic value series.
• Base Price Alignment : Each asset is normalized to its starting price at the chosen date.
• Dynamic Portfolio Table : Displays symbols, normalized weights (%), equivalent shares (based on each asset’s start price, sums to 100 shares), and a total row that always sums to 100%.
• Multi-Asset Support : Works with stocks, ETFs, indices, crypto, or any TradingView-compatible symbol.
⚙️ Configuration
Flexible Portfolio Setup
• Add up to 15 assets with custom weight inputs.
• You can enter any arbitrary numbers (e.g. 30, 15, 55).
• The script automatically normalizes all weights so the total allocation always equals 100%.
Start Date Selection
• Choose any custom start date to normalize all assets.
• The portfolio value is then scaled relative to the main chart symbol, so you can directly compare portfolio performance against benchmarks like SPY or QQQ.
Chart Styles
• Candlestick chart
• Heikin Ashi chart
• Line chart
Custom Display
• Adjustable colors and line widths
• Optionally display asset list, normalized weights, and equivalent shares
⚙️ How It Works
• Fetch OHLC data for each asset.
• Normalizes weights internally so totals = 100%.
• Stores each asset’s base price at the selected start date.
• Calculates equivalent “shares” for each allocation.
• Builds a synthetic portfolio value series by summing weighted contributions.
• Renders as Candlestick, Heikin Ashi, or Line chart.
• Adds a portfolio info table for clarity.
⚠️ Notes
• This script is for visualization only . It does not place trades or auto-rebalance.
• Weight inputs are automatically normalized, so you don’t need to enter exact percentages.
Индикатор