MAD Adaptive Trend Score [BackQuant]MAD Adaptive Trend Score
Overview
MAD Adaptive Trend Score is a trend oscillator built from a Median Absolute Deviation-based price filter and a multi-lookback relative-position score.
The indicator first calculates a rolling median and MAD from the selected source. Price deviation from the median is then clipped to a configurable MAD envelope, producing the MAD Adaptive Filter.
The current value of that filtered series is then compared with a range of its previous values. Each comparison contributes either +1 or -1 to a Trend Score.
The result is a bounded directional score that can be used with separate bullish and bearish thresholds to create a persistent trend state.
The script includes:
Exact rolling median and MAD calculations.
MAD-based clipping of source movement.
Configurable multi-lookback Trend Score.
Separate long and short regime thresholds.
Optional filter overlay on the main chart.
Trend candle colouring and signals.
Reference levels and alerts.
MAD Adaptive Filter
The first stage calculates the rolling median of the selected Source over the MAD Length.
It then calculates Median Absolute Deviation:
MAD = Median(|X - Median(X)|)
Raw MAD is multiplied by 1.4826:
Scaled MAD = Raw MAD × 1.4826
with a minimum value based on the instrument's minimum tick.
The 1.4826 factor is commonly used to scale MAD to approximately the same scale as standard deviation when the underlying distribution is normal.
The indicator then measures:
Deviation = Source - Rolling Median
and defines the maximum permitted deviation as:
Maximum Deviation = Scaled MAD × MAD Multiplier
The source deviation is clipped to this range before being added back to the median.
Conceptually:
If Source remains inside the MAD envelope, the filter follows Source.
If Source moves above the envelope, the filter is limited to the upper MAD boundary.
If Source moves below the envelope, the filter is limited to the lower MAD boundary.
The MAD Adaptive Filter is therefore not a conventional moving average. It is a source series whose distance from its rolling median is limited by the current MAD-derived envelope.
MAD Multiplier
MAD Multiplier controls the permitted distance between the filtered value and the rolling median.
Lower values:
Create a tighter envelope.
Clip more of the source movement.
Keep the filter closer to the median.
Higher values:
Create a wider envelope.
Allow more source movement through unchanged.
Make the filter follow price more closely.
Trend Score
The second stage scores the current MAD Filter against several previous values of the same filtered series.
For every lookback between Score Lookback Start and End:
+1 if the current MAD Filter is above the historical MAD Filter.
-1 otherwise.
The final Trend Score is the sum of all comparisons.
If N historical values are being compared, the theoretical score range is:
-N to +N
For the default 1-to-45 range, 45 comparisons are made, so the score can range from -45 to +45.
What the score represents
A high positive score means the current MAD-filtered value is above most of the historical filtered values being compared.
A strongly negative score means it is above very few of them.
For example, with 45 comparisons:
A score near +45 means the current filtered value is above nearly the entire comparison range.
A score near 0 means the comparisons are more evenly divided.
A score near -45 means the current filtered value is below, or equal to, nearly all of them.
The score is therefore best understood as a relative position / trend score of the filtered series.
It is not a return forecast or probability of future direction.
Why use several lookbacks?
Comparing the current filter with only one previous value would effectively reduce the calculation to short-term slope.
Using many previous values instead measures where the current filtered level sits relative to a broader section of its history.
A steadily rising filtered series will generally move toward higher positive scores because the current value becomes greater than an increasing number of historical values.
During sustained weakness, the opposite occurs.
Score Lookback Start and End
These settings define which historical MAD Filter values participate in the score.
For example:
Start = 1
End = 45
compares the current filter against each filtered value from 1 through 45 bars ago.
A shorter range:
Responds more quickly to recent changes.
Creates a smaller score range.
A longer range:
Includes more historical comparisons.
Produces a broader measure of relative trend position.
Usually changes more gradually.
Because the score range depends on the number of comparisons, threshold settings should be chosen with the selected score range in mind.
Trend State
The script converts the Trend Score into a persistent bullish or bearish signal state.
The bullish and bearish rules are deliberately separate.
Bullish condition
The signal becomes bullish when:
Trend Score > Long Threshold
Once bullish, the state remains bullish until a valid bearish condition occurs.
Bearish condition
The signal becomes bearish when the score crosses downward through the Short Threshold:
Previous Score >= Short Threshold
Current Score < Short Threshold
The bearish condition therefore requires an actual downward threshold crossing rather than simply remaining below the level.
Why use separate thresholds?
Using different bullish and bearish levels introduces persistence into the regime.
The signal does not need to reverse whenever the score crosses zero.
For example, with:
Long Threshold = 40
Short Threshold = -6
the score must reach a strongly positive state before the model turns bullish, but the bullish state can persist through a substantial amount of score deterioration before a bearish transition occurs.
This creates a form of threshold hysteresis and reduces rapid switching around a single center level.
The thresholds are fully configurable and do not need to be symmetrical.
Initial state
The signal begins neutral.
A bullish state can be established once the Long Threshold condition is satisfied.
A bearish state requires a valid downward crossing of the Short Threshold.
Signal markers are shown only when an established bullish state changes to bearish or an established bearish state changes to bullish.
The initial transition from neutral does not produce a long/short marker.
Reference Lines
The optional dashed reference lines display the Long and Short Thresholds directly in the oscillator pane.
These levels correspond to the actual regime settings and can be useful when visually tracking how the Trend Score approaches a possible state change.
MAD Filter Overlay
The MAD Adaptive Filter can optionally be plotted directly on the main price chart.
This makes it possible to compare:
Raw price.
The rolling-median/MAD envelope response.
The active trend colour.
The overlay uses the same bullish or bearish state colour as the oscillator.
Trend Candles
Optional chart candles are coloured from the stored trend state:
Bullish state = Long Color.
Bearish state = Short Color.
The colour represents the indicator's trend regime rather than the direction of each individual candle.
Background Colour
An optional transparent background can also display the current trend regime on the main chart.
This is purely visual and does not alter the calculation.
How to interpret it
Strong positive score
The current MAD Filter is above most values in the selected historical comparison range.
This typically accompanies a relatively strong upward position in the filtered trend.
Falling score while still bullish
The filtered trend is losing relative strength, but the Short Threshold has not yet been crossed.
The persistent state therefore remains bullish.
Short Threshold crossing
The score has deteriorated far enough to cross below the selected bearish boundary, changing the stored state to bearish.
Rising score while bearish
The score can recover substantially while the trend remains bearish.
A new bullish state is not established until the score exceeds the Long Threshold.
How to use the indicator
The indicator can be used as:
A directional trend filter.
A persistent bullish/bearish regime indicator.
A way to measure the relative position of a MAD-filtered price series.
A confirmation tool alongside other price or market-structure analysis.
The score itself can also provide additional context beyond the binary trend colour.
For example, a bullish regime with a score near its maximum is different from a bullish regime whose score has already fallen substantially toward the bearish threshold.
Input Guide
MAD Length
Controls the rolling sample used to calculate the median and Median Absolute Deviation.
Shorter values adapt more quickly.
Longer values produce a broader statistical reference window.
MAD Multiplier
Controls how far the filtered source may move away from its rolling median.
Lower values produce stronger clipping.
Higher values allow the filter to follow Source more closely.
Score Lookback Start / End
Defines the historical MAD Filter values used in the Trend Score comparisons.
Long Threshold
Score level that must be exceeded to establish a bullish state.
Short Threshold
Level that must be crossed downward to establish a bearish state.
Data Window
The script exposes:
Rolling Median.
Raw MAD.
Scaled MAD.
These values can help show how the underlying MAD filter is being constructed.
Limitations
The indicator is reactive rather than predictive.
The score measures the current filtered value relative to historical filtered values; it does not estimate future returns.
Threshold selection can materially change signal frequency and persistence.
A very tight MAD Multiplier can suppress meaningful movement along with noise.
A very wide MAD Multiplier makes the filter increasingly similar to the original Source.
Long score ranges can improve persistence but also delay changes in regime.
Strong trends can keep the score near an extreme for extended periods.
Alerts
The script includes:
MAD Trend Score Long: stored signal changes from bearish to bullish.
MAD Trend Score Short: stored signal changes from bullish to bearish.
Summary
MAD Adaptive Trend Score combines two simple ideas.
First, the selected Source is constrained around a rolling median using Median Absolute Deviation. Source movement inside the MAD envelope passes through normally, while movement beyond the envelope is clipped to the current boundary.
Second, the current filtered value is compared with a configurable range of its own historical values.
Those comparisons are summed into a Trend Score, with positive values indicating that the current filtered level is above more of the historical comparison range and negative values indicating the opposite.
Separate Long and Short Thresholds then convert the score into a persistent bullish or bearish regime.
The result is a MAD-based filtered series and relative-position trend score for experimenting with trend persistence and threshold behaviour. Индикатор

Khabib Takedown Fractal Nest Breakdown ViprasolKhabib Takedown — Fractal Nest Breakdown 🤼
CONCEPT
This tool looks for SELF-SIMILARITY in a decline: a big bearish leg (lower high -> lower low)
with a smaller bearish leg nested inside it that is a scaled copy — same shape, a fraction of
the size. When the small "fractal" completes in the direction of the big one (a break of the
last low), the structure grounds price -> SHORT. It is a fractal-echo measurement, not a plain
lower-low. The nesting ratio between the small leg and the big leg is the core filter.
HOW IT DETECTS
- Swings are found with confirmed pivot highs/lows (left/right bar lookback) and chained into a
lightweight zigzag.
- The tool reads the last four alternating swings (high, low, high, low).
- Big leg = first high minus first low; small leg = second high minus second low.
- A valid nest requires: lower high and lower low (bearish structure); big leg >= (Min big x ATR);
small leg positive; and the nesting ratio (small/big) inside the band .
- The signal fires when price closes below the most recent swing low and the bar closes red.
- ATR (Wilder) scales the minimum big-leg size across instruments and timeframes.
ENTRY / STOP / TARGET
- Entry: SHORT on the close of the confirming (red) bar that breaks the last low.
- Stop: above the second (inner) swing high plus an ATR buffer (default 0.3 x ATR).
- Target: entry minus R multiple x risk (default 2R, where risk = stop distance).
- The script draws the big leg and the nested small leg, plus filled TP and SL zones that extend
to the right until price touches one of them.
NON-REPAINTING
Pivots are only used once fully confirmed (they require the right-side bars), and the signal is
evaluated on bar close (barstate.isconfirmed). Drawings are created on the confirmed bar. The tool
does not repaint completed signals. Live, the forming bar can still change until it closes, as with
any bar-close tool.
FEATURES
- Fractal nesting (scaled self-similar legs), not a plain lower-low break.
- ATR-scaled minimum big-leg requirement and adjustable nesting-ratio band.
- Automatic R-multiple TP and ATR-buffered SL, drawn as zones that extend until hit.
- One-trade-at-a-time option and a minimum-bars-between-signals gap to reduce clustering.
- On-chart status table (open trades) and an alertcondition for automation.
INPUTS OVERVIEW
- Swing pivot left/right bars: swing sensitivity.
- Nesting ratio band (ratLo/ratHi): how close in scale the small leg must be to the big leg.
- Min big leg (x ATR) and ATR length: minimum move and volatility scaling.
- TP R multiple, SL buffer (x ATR), min bars between signals, one-trade-at-a-time.
- Visual colors, label offset, and zone transparency.
HOW TO USE
1. Add to any liquid symbol and timeframe; start with defaults.
2. Tighten the nesting-ratio band for stricter self-similarity, or widen it for more signals.
3. Raise Min big leg (x ATR) to demand larger, cleaner declines before a nest counts.
4. Use the drawn TP/SL zones for context; set an alert on the signal for hands-off monitoring.
5. Combine with your own trend/context read before acting.
LIMITATIONS
- This is a pattern/education tool, not a signal service, and not financial advice.
- Breakdown patterns fail; nesting geometry is a filter, not a guarantee. Losing signals will occur.
- Pivot confirmation adds inherent lag (it needs bars to the right of a swing to confirm).
- Very choppy or illiquid markets can produce misshapen legs and weak signals.
- Requires user discretion, risk management, and position sizing. No performance is implied.
CREDITS
The name is an inspirational sports homage only; it does not imply any endorsement or affiliation.
ATR uses Wilder's average true range. Pivot/zigzag swing detection uses standard public techniques.
The fractal-nest (scaled self-similar leg) geometry, the detection assembly, and the trade/zone
visualization are original Viprasol work.
Original Viprasol work; no third-party Pine code reused.
Индикатор

Session ATR Risk ToolSession ATR Risk Tool
## Overview
The Session ATR Risk Tool is a discretionary **risk-management and trade-planning overlay**. It sizes a stop loss from market volatility, projects fixed reward-to-risk targets (1:1, 1:2, 1:3), and draws a standard-deviation ladder so you can see your full trade geometry on the chart before you enter. It also estimates a contract count from a fixed dollar risk, and prints a context table of intraday, daily and weekly volatility.
It is built and tuned for Micro E-mini Nasdaq-100 (MNQ) intraday trading, but every parameter is exposed as an input, so it works on any symbol once you set the correct point value.
This tool does **not** generate buy/sell signals and makes no claim about win rate or profitability. It is a visualization and planning aid only.
## What makes it different
Most reward-to-risk tools place lines a fixed number of ticks or a single ATR away. This tool adds three things in one package:
1. **Two selectable stop engines.** The stop distance can be derived from either the chart-timeframe ATR (small, realistic intraday stops) or from a rolling average of completed *session* ranges (swing-sized stops). You choose which volatility regime sizes your risk.
2. **A standard-deviation ladder denominated in your own stop distance.** Instead of arbitrary fib or price-percent levels, each rung is a multiple (−0.5, 1, 2, 3, 4 by default, all editable) of the exact ATR-based stop distance, projected from entry. One "sd" on the chart always equals one unit of the risk you are actually taking.
3. **A volatility context table.** Intraday ATR, averaged session range, daily ATR(14) and weekly ATR(14) are shown side by side so the chosen stop can be judged against higher-timeframe volatility at a glance.
## How it works
- **Session range capture.** The script tracks the high and low of each completed session window (default 09:30–16:00 exchange time) and stores the high-low range. It keeps a rolling buffer of the most recent N sessions (default 10) and averages them to produce a "session ATR" in points.
- **Intraday ATR.** A standard ATR of configurable length is calculated on the chart timeframe for scalp-sized stops.
- **Stop distance.** `Stop distance = chosen basis × ATR multiplier`, where the basis is either the intraday ATR or the averaged session range. The multiplier lets you tighten or widen the stop.
- **Trade geometry.** From the entry price (live price by default, or a fixed price you type in) and the trade direction, the tool places the stop one stop-distance against you, then projects targets at 1×, 2× and 3× the stop distance for clean 1:1 / 1:2 / 1:3 reward-to-risk.
- **Standard-deviation ladder.** Each ladder rung is plotted at `entry + direction × stop distance × deviation`, giving an evenly scaled map of where price sits relative to your risk unit.
- **Position-size estimate.** Dollar risk per contract = stop distance × point value. Estimated contracts = floor(risk per trade ÷ dollar risk per contract). This is an arithmetic estimate for planning, not an order-routing instruction.
- **Higher-timeframe context.** Daily and weekly ATR(14) are pulled from confirmed higher-timeframe bars (non-repainting) for the context table.
All levels are drawn as faded horizontal rays anchored to the bar grid, so they stay locked to the candles when you pan or zoom. Drawings rebuild on the most recent bar to keep the chart clean.
## How to use it
1. Add the tool to an intraday chart of the instrument you trade.
2. Set **$ per Point** for your instrument (MNQ = 2.0, NQ = 20.0, MES = 5.0, etc.) and your **Risk per Trade ($)**.
3. Choose your **Stop Basis** — "Intraday ATR" for scalps and intraday entries, "Session Range" for wider, swing-style stops.
4. Adjust the **ATR Multiplier** to set how far the stop sits from entry. As a starting guide, roughly 1.0–2.0× with Intraday ATR on a 1–5 minute chart; if using Session Range, scale the multiplier down (around 0.10–0.20×) because the session range is much larger.
5. Set **Trade Direction** (Long or Short). Leave **Entry Price** at 0 to anchor the levels to live price, or type your actual fill price to lock the geometry in place after entry.
6. Read your plan off the chart: the Stop, the 1:1 / 1:2 / 1:3 targets, the standard-deviation ladder, and the info table showing the stop in points and dollars plus an estimated contract count.
## Inputs
- **Session Window / Sessions to Average** — defines the session and how many completed sessions feed the averaged session range.
- **Stop Basis / Intraday ATR Length / ATR Multiplier** — select and tune the volatility source for the stop.
- **Trade Direction / Entry Price** — direction toggle and optional fixed entry.
- **$ per Point / Risk per Trade ($)** — instrument tick value and account risk used for the size estimate.
- **SDev Ladder deviations** — the five editable ladder multiples.
- **Visual controls** — ray length back/forward, table toggle, and colors for up, down and entry levels.
## Notes and limitations
- The contract-count figure is an arithmetic estimate from your inputs. It is not connected to a broker and places no orders. Always confirm size and risk in your own platform.
- "Session ATR" here means the averaged high-low **range** of recent sessions, not a true-range calculation; it is intentionally a wider, regime-level measure.
- Higher-timeframe ATR values use confirmed bars to avoid repainting.
- Reward-to-risk targets are fixed geometric projections; they are not predictions of price reaching those levels.
- This script is a planning and visualization tool only. It is not financial advice and does not guarantee any outcome. Индикатор

Индикатор

Индикатор

Индикатор

Индикатор

Session Opening Range Breakout (ORBO)This strategy automates a classic Opening Range Breakout (ORBO) approach: it builds a price range for the first minutes after the market opens, then looks for strong breakouts above or below that range to catch early directional moves.
Concept
The idea behind ORBO is simple:
The first minutes after the session open are often highly informative.
Price forms an “opening range” that acts as a mini support/resistance zone.
A clean breakout beyond this zone can lead to high-momentum moves.
This script turns that logic into a fully backtestable strategy in TradingView.
How the strategy works
Opening Range Session
Default session: 09:30–09:50 (exchange time)
During this window, the script tracks:
orHigh → highest high within the session
orLow → lowest low within the session
This forms your Opening Range for the day.
Breakout Logic (after the window ends)
Once the defined session ends:
Long Entry:
If the close crosses above the Opening Range High (orHigh),
→ strategy.entry("OR Long", strategy.long) is triggered.
Short Entry:
If the close crosses below the Opening Range Low (orLow),
→ strategy.entry("OR Short", strategy.short) is triggered.
Only one opening range per day is considered, which keeps the logic clean and easy to interpret.
Daily Reset
At the start of a new trading day, the script resets:
orHigh := na
orLow := na
A fresh Opening Range is then built using the next session’s 09:30–09:50 candles.
This ensures entries are always based on today’s structure, not yesterday’s.
Visuals & Inputs
Inputs:
Opening range session → default: "0930-0950"
Show OR levels → toggle visibility of OR High / Low lines
Fill range body → optional shaded zone between OR High and OR Low
Chart visuals:
A green line marks the Opening Range High.
A red line marks the Opening Range Low.
Optional yellow fill highlights the entire OR zone.
Background shading during the session shows when the range is currently being built.
These visuals make it easy to see:
Where the OR sits relative to current price
How clean / noisy the breakout was
How often price respects or rejects the opening zone
Backtesting & Optimization
Because this is written as a strategy():
You can use TradingView’s Strategy Tester to view:
Win rate
Net profit
Drawdown
Profit factor
Equity curve
Ideas to experiment with:
Change the session window (e.g., 09:15–09:45, 10:00–10:30)
Apply to different:
Markets: indices, FX, crypto, stocks
Timeframes: 1m / 5m / 15m
Add your own:
Stop Loss & Take Profit levels
Time filters (only trade certain days / times)
Volatility filters (e.g., ATR, range size thresholds)
Higher-timeframe trend filter (e.g., only take longs above 200 EMA)
Стратегия

TitanGrid L/S SuperEngineTitanGrid L/S SuperEngine
Experimental Trend-Aligned Grid Signal Engine for Long & Short Execution
🔹 Overview
TitanGrid is an advanced, real-time signal engine built around a tactical grid structure.
It manages Long and Short trades using trend-aligned entries, layered scaling, and partial exits.
Unlike traditional strategy() -based scripts, TitanGrid runs as an indicator() , but includes its own full internal simulation engine.
This allows it to track capital, equity, PnL, risk exposure, and trade performance bar-by-bar — effectively simulating a custom backtest, while remaining compatible with real-time alert-based execution systems.
The concept was born from the fusion of two prior systems:
Assassin’s Grid (grid-based execution and structure) + Super 8 (trend-filtering, smart capital logic), both developed under the AssassinsGrid framework.
🔹 Disclaimer
This is an experimental tool intended for research, testing, and educational use.
It does not provide guaranteed outcomes and should not be interpreted as financial advice.
Use with demo or simulated accounts before considering live deployment.
🔹 Execution Logic
Trend direction is filtered through a custom SuperTrend engine. Once confirmed:
• Long entries trigger on pullbacks, exiting progressively as price moves up
• Short entries trigger on rallies, exiting as price declines
Grid levels are spaced by configurable percentage width, and entries scale dynamically.
🔹 Stop Loss Mechanism
TitanGrid uses a dual-layer stop system:
• A static stop per entry, placed at a fixed percentage distance matching the grid width
• A trend reversal exit that closes the entire position if price crosses the SuperTrend in the opposite direction
Stops are triggered once per cycle, ensuring predictable and capital-aware behavior.
🔹 Key Features
• Dual-side grid logic (Long-only, Short-only, or Both)
• SuperTrend filtering to enforce directional bias
• Adjustable grid spacing, scaling, and sizing
• Static and dynamic stop-loss logic
• Partial exits and reset conditions
• Webhook-ready alerts (browser-based automation compatible)
• Internal simulation of equity, PnL, fees, and liquidation levels
• Real-time dashboard for full transparency
🔹 Best Use Cases
TitanGrid performs best in structured or mean-reverting environments.
It is especially well-suited to assets with the behavioral profile of ETH — reactive, trend-intraday, and prone to clean pullback formations.
While adaptable to multiple timeframes, it shows strongest performance on the 15-minute chart , offering a balance of signal frequency and directional clarity.
🔹 License
Published under the Mozilla Public License 2.0 .
You are free to study, adapt, and extend this script.
🔹 Panel Reference
The real-time dashboard displays performance metrics, capital state, and position behavior:
• Asset Type – Automatically detects the instrument class (e.g., Crypto, Stock, Forex) from symbol metadata
• Equity – Total simulated capital: realized PnL + floating PnL + remaining cash
• Available Cash – Capital not currently allocated to any position
• Used Margin – Capital locked in open trades, based on position size and leverage
• Net Profit – Realized gain/loss after commissions and fees
• Raw Net Profit – Gross result before trading costs
• Floating PnL – Unrealized profit or loss from active positions
• ROI – Return on initial capital, including realized and floating PnL. Leverage directly impacts this metric, amplifying both gains and losses relative to account size.
• Long/Short Size & Avg Price – Open position sizes and volume-weighted average entry prices
• Leverage & Liquidation – Simulated effective leverage and projected liquidation level
• Hold – Best-performing hold side (Long or Short) over the session
• Hold Efficiency – Performance efficiency during holding phases, relative to capital used
• Profit Factor – Ratio of gross profits to gross losses (realized)
• Payoff Ratio – Average profit per win / average loss per loss
• Win Rate – Percent of profitable closes (including partial exits)
• Expectancy – Net average result per closed trade
• Max Drawdown – Largest recorded drop in equity during the session
• Commission Paid – Simulated trading costs: maker, taker, funding
• Long / Short Trades – Count of entry signals per side
• Time Trading – Number of bars spent in active positions
• Volume / Month – Extrapolated 30-day trading volume estimate
• Min Capital – Lowest equity level recorded during the session
🔹 Reference Ranges by Strategy Type
Use the following metrics as reference depending on the trading style:
Grid / Mean Reversion
• Profit Factor: 1.2 – 2.0
• Payoff Ratio: 0.5 – 1.2
• Win Rate: 50% – 70% (based on partial exits)
• Expectancy: 0.05% – 0.25%
• Drawdown: Moderate to high
• Commission Impact: High
Trend-Following
• Profit Factor: 1.5 – 3.0
• Payoff Ratio: 1.5 – 3.5
• Win Rate: 30% – 50%
• Expectancy: 0.3% – 1.0%
• Drawdown: Low to moderate
Scalping / High-Frequency
• Profit Factor: 1.1 – 1.6
• Payoff Ratio: 0.3 – 0.8
• Win Rate: 80% – 95%
• Expectancy: 0.01% – 0.05%
• Volume / Month: Very high
Breakout Strategies
• Profit Factor: 1.4 – 2.2
• Payoff Ratio: 1.2 – 2.0
• Win Rate: 35% – 60%
• Expectancy: 0.2% – 0.6%
• Drawdown: Can be sharp after failed breakouts
🔹 Note on Performance Simulation
TitanGrid includes internal accounting of fees, slippage, and funding costs.
While its logic is designed for precision and capital efficiency, performance is naturally affected by exchange commissions.
In frictionless environments (e.g., zero-fee simulation), its high-frequency logic could — in theory — extract substantial micro-edges from the market.
However, real-world conditions introduce limits, and all results should be interpreted accordingly. Индикатор

[Kpt-Ahab] Poor Mans Orderflow SimulatorScript Description – Poor Mans Orderflow Simulator
Purpose of the Script
This script simulates a simplified order flow approach ("Poor Man's Orderflow") without access to actual Bid/Ask data. The goal is to detect, quantify, and visualize patterns such as absorption, impulsive moves, and structured re-entry behaviors.
Calculation Logic
Absorption Candles
A candle is classified as "absorption" if:
The ratio of body size to full candle range is below a defined threshold,
Volume is significantly higher than the average of the last N periods,
The candle direction is negative (for long absorption) or positive (for short absorption).
These conditions define a candle with high activity but minimal price movement in the respective direction.
Impulse Candles
A candle is classified as "impulse" if:
The body-to-range ratio is high (indicating a strong directional move),
Volume exceeds the average significantly,
The price closes in the direction of the candle body (bullish or bearish).
Additionally, the average range of previous candles serves as a minimum benchmark for the impulse.
Cluster Detection
A cluster is detected when:
A minimum number of absorption candles is counted within a defined lookback period,
Either the long or short version of the absorption logic is used,
The result is a binary condition: cluster active or inactive.
Entry Signals (Re-entry)
An entry signal is generated when:
One or more absorption candles occurred in the last two bars,
A pullback against the direction of absorption occurs,
The current candle shows a directional move confirmed by a close in the expected direction.
These re-entry signals are evaluated separately for long and short scenarios.
Cluster-Confirmed Signals
A separate signal is generated when a valid re-entry setup occurs while a cluster is active. This represents a combined logic condition.
Alert Logic
The script provides a multi-layer alert framework:
Signal selection (Alertmode):
The user defines which signal type should trigger an alert (e.g. re-entry only, cluster only, combination, or impulse).
Optional filter (Filtermode):
A secondary filter limits alerts to cases where an additional condition (e.g. absorption cluster) is active.
Signal output:
As a simple binary value (+1 / –1) for classic alerts,
Or via an encoded Multibit signal, compatible with other modules in the djmad ecosystem.
These alerts are intended for integration with external systems or for use within platform-native visual or automation features. Индикатор

Индикатор

Ultra Trade JournalThe Ultra Trade Journal is a powerful TradingView indicator designed to help traders meticulously document and analyze their trades. Whether you're a novice or an experienced trader, this tool offers a clear and organized way to visualize your trading strategy, monitor performance, and make informed decisions based on detailed trade metrics.
Detailed Description
The Ultra Trade Journal indicator allows users to input and visualize critical trade information directly on their TradingView charts.
.........
User Inputs
Traders can specify entry and exit prices , stop loss levels, and up to four take profit targets.
.....
Dynamic Plotting
Once the input values are set, the indicator automatically plots horizontal lines for entry, exit, stop loss, and each take profit level on the chart. These lines are visually distinct, using different colors and styles (solid, dashed, dotted) to represent each element clearly.
.....
Live Position Tracking
If enabled, the indicator can adjust the exit price in real-time based on the current market price, allowing traders to monitor live positions effectively.
.....
Tick Calculations
The script calculates the number of ticks between the entry price and each exit point (stop loss and take profits). This helps in understanding the movement required for each target and assessing the potential risk and reward.
.....
Risk-Reward Ratios
For each take profit level, the indicator computes the risk-reward (RR) ratio by comparing the ticks at each target against the stop loss ticks. This provides a quick view of the potential profitability versus the risk taken.
.....
Comprehensive Table Display
A customizable table is displayed on the chart, summarizing all key trade details. This includes the entry and exit prices, stop loss and take profit levels, tick counts, and their respective RR ratios.
Users can adjust the table's Position and text color to suit their preferences.
.....
Visual Enhancements
The indicator uses adjustable background shading between entry and stop loss/take profit lines to visually represent potential trade outcomes. This shading adjusts based on whether the trade is long or short, providing an intuitive understanding of trade performance.
.........
Overall, the Ultra Trade Journal combines visual clarity with detailed analytics, enabling traders to keep a well-organized record of their trades and enhance their trading strategies through insightful data. Индикатор

Стратегия

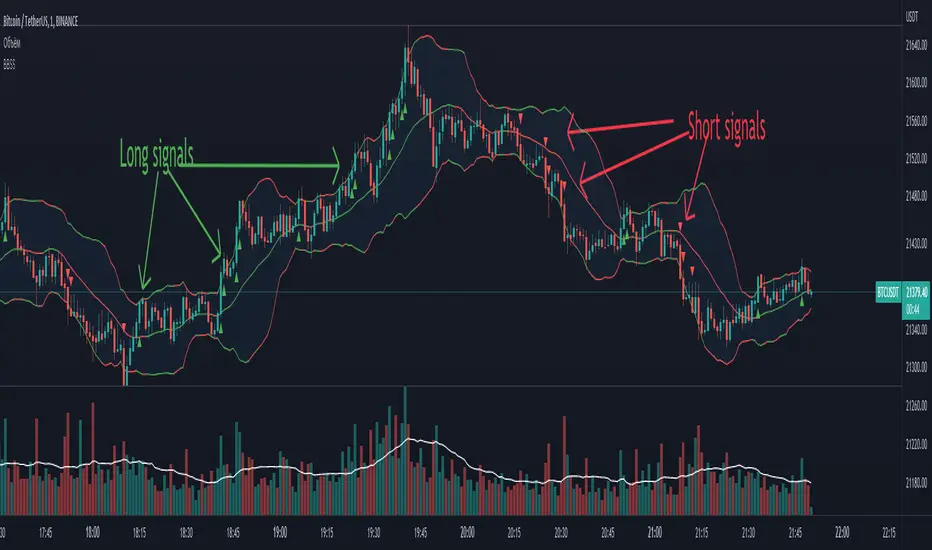
Bollinger Bands - Breakout StrategyThe Bollinger Bands - Breakout Strategy is a trend-following optimized for short-term trading in the crypto market. This strategy employs the Bollinger Bands, a widely recognized technical indicator, as its primary instrument for pinpointing potential trades. It is capable of executing both long and short positions, depending on whether the market is in a spot or futures, and is particularly effective in trending markets.
The strategy boasts a high degree of configurability, allowing users to set the Bollinger Bands period and deviation, trend filter, volatility filter, trade direction filter, rate of change filter, and date filter. Furthermore, it offers options for Take Profit, Stop Loss, and Trailing Stop for both long and short positions, ensuring a comprehensive risk management approach. The inclusion of a maximum intraday loss feature adds another layer of protection, making this strategy a valuable tool for traders seeking a professional and adaptable trading system.
Name : Bollinger Bands - Breakout Strategy
Category : Trend Follower based on Bollinger Bands
Operating mode : Long and Short on Futures or Long on Spot
Trade duration : Intraday
Timeframe : 2H, 3H, 4H, 5H
Market : Crypto
Suggested usage : Trending Markets
Entry : When the price crosses above or below the Bollinger Bands
Exit : Opposite Cross or Profit target, Trailing stop or Stop loss
Configuration :
- Bollinger Bands period and deviation
- Trend Filter
- Volatility Filter
- Trade direction filter
- Rate of Change filter
- Date Filter (for backtesting purposes)
- Take Profit, Stop Loss and Trailing Stop for long and short positions
- Risk Management: Max Intraday Loss
Backtesting :
⁃ Exchange: BINANCE
⁃ Pair: BTCUSDT.P
⁃ Timeframe: 4H
⁃ Fee: 0.025%
⁃ Slippage: 1
- Initial Capital: 10000 USDT
- Position sizing: 10% of Equity
- Start : 2019-09-19 (Out Of Sample from 2022-12-23)
- Bar magnifier: on
Credits :
- LucF of Pine Coders for f_security function to avoid repainting using security.
- QuantNomad for Monthly Table.
Disclaimer : Risk Management is crucial, so adjust stop loss to your comfort level. A tight stop loss can help minimise potential losses. Use at your own risk.
How you or we can improve? Source code is open so share your ideas!
Leave a comment and smash the boost button!
Thanks for your attention, happy to support the TradingView community. Стратегия

Индикатор

Индикатор

Стратегия

Стратегия

Стратегия

Ichimoku Cloud with ADX (By Coinrule)The Ichimoku Cloud is a collection of technical indicators that show support and resistance levels, as well as momentum and trend direction. It does this by taking multiple averages and plotting them on a chart. It also uses these figures to compute a “cloud” that attempts to forecast where the price may find support or resistance in the future.
The Ichimoku Cloud was developed by Goichi Hosoda, a Japanese journalist, and published in the late 1960s. It provides more data points than the standard candlestick chart. While it seems complicated at first glance, those familiar with how to read the charts often find it easy to understand with well-defined trading signals.
The Ichimoku Cloud is composed of five lines or calculations, two of which comprise a cloud where the difference between the two lines is shaded in.
The lines include a nine-period average, a 26-period average, an average of those two averages, a 52-period average, and a lagging closing price line.
The cloud is a key part of the indicator. When the price is below the cloud, the trend is down. When the price is above the cloud, the trend is up.
The above trend signals are strengthened if the cloud is moving in the same direction as the price. For example, during an uptrend, the top of the cloud is moving up, or during a downtrend, the bottom of the cloud is moving down.
DMI is simple to interpret. When +DI > - DI, it means the price is trending up. On the other hand, when -DI > +DI , the trend is weak or moving on the downside. The ADX does not give an indication about the direction but about the strength of the trend.
Typically values of ADX above 25 mean that the trend is steeply moving up or down, based on the -DI and +D positioning. This script aims to capture swings in the DMI, and thus, in the trend of the asset, using a contrarian approach.
Trading on high values of ADX , the strategy tries to spot extremely oversold and overbought conditions. Values of ADX above 45 may suggest that the trend has overextended and is may be about to reverse.
This strategy combines the Ichimoku Cloud with the ADX indicator to better enter trades.
Long/Short orders are placed when these basic signals are triggered.
Long Position:
Tenkan-Sen is above the Kijun-Sen
Chikou-Span is above the close of 26 bars ago
Close is above the Kumo Cloud
MACD line crosses over the signal line
-DI is greater than +DI
ADX is greater than 45
Short Position:
Tenkan-Sen is below the Kijun-Sen
Chikou-Span is below the close of 26 bars ago
Close is below the Kumo Cloud
MACD line crosses under the signal line
+DI is greater than -DI
ADX is less than 45
The script is backtested from 1 January 2022 and provides good returns.
The strategy assumes each order is using 30% of the available coins to make the results more realistic and to simulate you only ran this strategy on 30% of your holdings. A trading fee of 0.1% is also taken into account and is aligned to the base fee applied on Binance.
This script also works well on MATIC (15m timeframe), ETH (5m timeframe), and SOL (15m timeframe). Стратегия

Индикатор

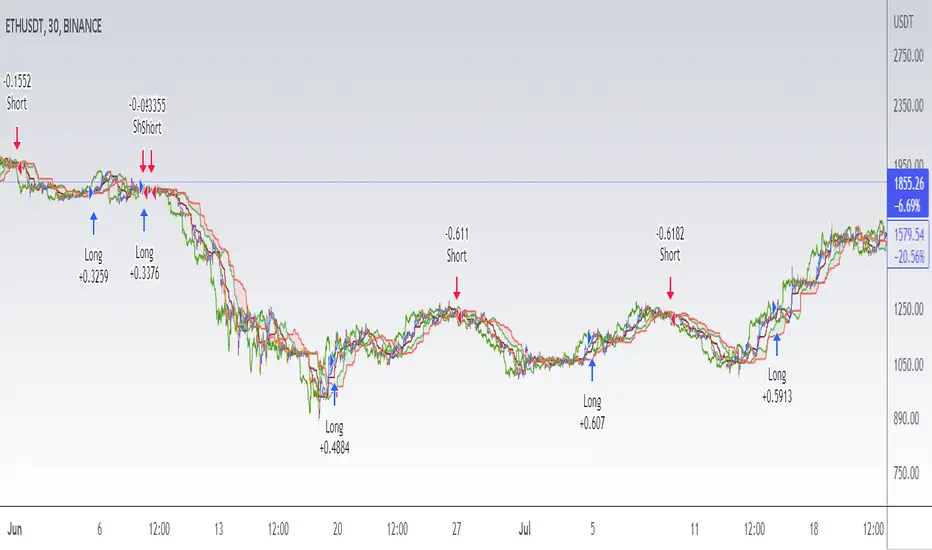
Ichimoku Cloud with MACD (By Coinrule)The Ichimoku Cloud is a collection of technical indicators that show support and resistance levels, as well as momentum and trend direction. It does this by taking multiple averages and plotting them on a chart. It also uses these figures to compute a “cloud” that attempts to forecast where the price may find support or resistance in the future.
The Ichimoku Cloud was developed by Goichi Hosoda, a Japanese journalist, and published in the late 1960s. It provides more data points than the standard candlestick chart. While it seems complicated at first glance, those familiar with how to read the charts often find it easy to understand with well-defined trading signals.
The Ichimoku Cloud is composed of five lines or calculations, two of which comprise a cloud where the difference between the two lines is shaded in.
The lines include a nine-period average, a 26-period average, an average of those two averages, a 52-period average, and a lagging closing price line.
The cloud is a key part of the indicator. When the price is below the cloud, the trend is down. When the price is above the cloud, the trend is up.
The above trend signals are strengthened if the cloud is moving in the same direction as the price. For example, during an uptrend, the top of the cloud is moving up, or during a downtrend, the bottom of the cloud is moving down.
The MACD is a trend following momentum indicator and provides identification of short-term trend direction. In this variation it utilises the 12-period as the fast and 26-period as the slow length EMAs, with signal smoothing set at 9.
This strategy combines the Ichimoku Cloud with the MACD indicator to better enter trades.
Long/Short orders are placed when three basic signals are triggered.
Long Position:
Tenkan-Sen is above the Kijun-Sen
Chikou-Span is above the close of 26 bars ago
Close is above the Kumo Cloud
MACD line crosses over the signal line
Short Position:
Tenkan-Sen is below the Kijun-Sen
Chikou-Span is below the close of 26 bars ago
Close is below the Kumo Cloud
MACD line crosses under the signal line
The script is backtested from 1 June 2022 and provides good returns.
The strategy assumes each order is using 30% of the available coins to make the results more realistic and to simulate you only ran this strategy on 30% of your holdings. A trading fee of 0.1% is also taken into account and is aligned to the base fee applied on Binance.
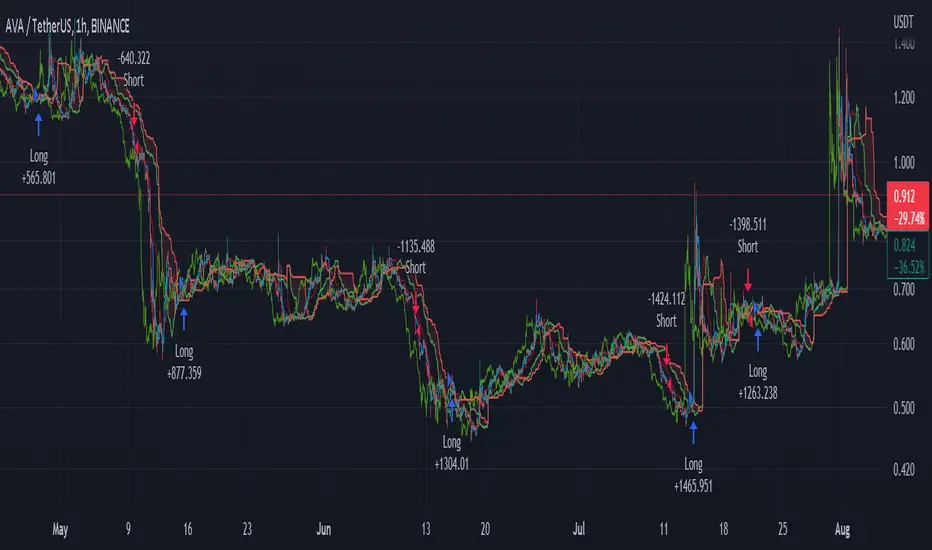
This script also works well on MATIC (1h timeframe), AVA (45m timeframe), and BTC (30m timeframe). Стратегия

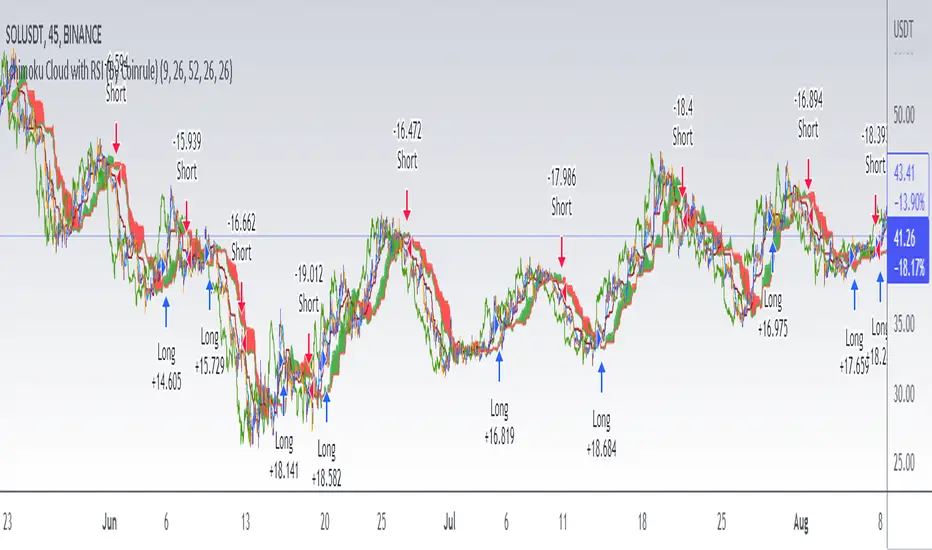
Ichimoku Cloud with RSI (By Coinrule)The Ichimoku Cloud is a collection of technical indicators that show support and resistance levels, as well as momentum and trend direction. It does this by taking multiple averages and plotting them on a chart. It also uses these figures to compute a “cloud” that attempts to forecast where the price may find support or resistance in the future.
The Ichimoku Cloud was developed by Goichi Hosoda, a Japanese journalist, and published in the late 1960s. It provides more data points than the standard candlestick chart. While it seems complicated at first glance, those familiar with how to read the charts often find it easy to understand with well-defined trading signals.
The Ichimoku Cloud is composed of five lines or calculations, two of which comprise a cloud where the difference between the two lines is shaded in.
The lines include a nine-period average, a 26-period average, an average of those two averages, a 52-period average, and a lagging closing price line.
The cloud is a key part of the indicator. When the price is below the cloud, the trend is down. When the price is above the cloud, the trend is up.
The above trend signals are strengthened if the cloud is moving in the same direction as the price. For example, during an uptrend, the top of the cloud is moving up, or during a downtrend, the bottom of the cloud is moving down.
This strategy combines the Ichimoku Cloud with the RSI indicator to better enter trades.
Long/Short orders are placed when three basic signals are triggered.
Long Position:
Tenkan-Sen is above the Kijun-Sen
Chikou-Span is above the close of 26 bars ago
Close is above the Kumo Cloud
RSI is greater less than 50
Short Position:
Tenkan-Sen is below the Kijun-Sen
Chikou-Span is below the close of 26 bars ago
Close is below the Kumo Cloud
RSI is greater than 50
The script is backtested from 1 June 2022 and provides good returns.
The strategy assumes each order is using 30% of the available coins to make the results more realistic and to simulate you only ran this strategy on 30% of your holdings. A trading fee of 0.1% is also taken into account and is aligned to the base fee applied on Binance.
This script also works well on SOL (45m timeframe), BNB (1h timeframe), and ETH (1h timeframe). Стратегия